
Why This Distinction Matters More Than Ever
In today’s digital economy, payments are no longer an afterthought — they are the platform. Yet many businesses misunderstand how platform payments differ from marketplace payments, especially when they scale globally.
If your fintech or SaaS solution involves payments between parties, this distinction isn’t just academic — it directly impacts your compliance, monetization, and user trust.
Let’s untangle these models and explore how they differ across operational layers, from settlement logic to regulatory responsibilities.
First Things First: What Are Platform Payments?
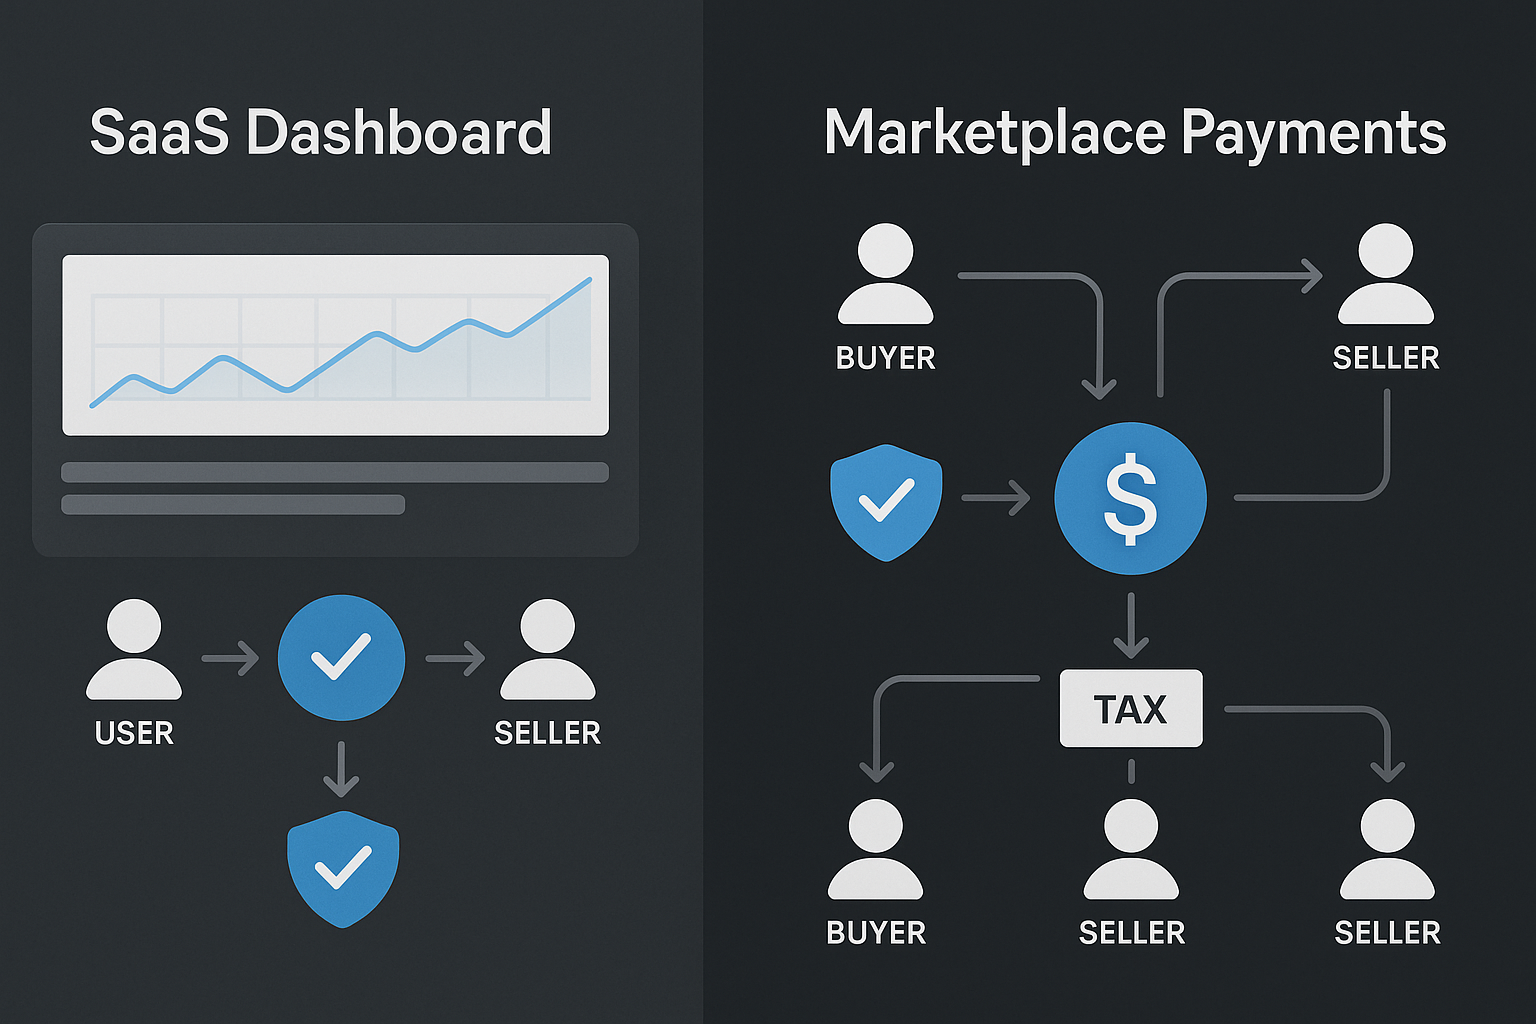
Platform payments occur when a software or service provider facilitates transactions between buyers and sellers on behalf of a single entity or business.
Here’s a good example: imagine a subscription platform for online fitness classes. When a customer pays, the money goes directly to the fitness trainer’s account — through the platform’s integrated payment system.
But in this model:
-
The platform doesn’t control the inventory or the pricing.
-
It enables payments, handles fees, and improves experience.
-
It may also act as a Payment Facilitator (PayFac) or integrate with one.
Platform payments are tightly woven into vertical SaaS, service aggregators, or creator economy tools.
“In platform payments, the software is the bridge — not the destination.”
What About Marketplace Payments ?
Marketplace payments involve a more intricate flow, where the platform hosts multiple independent sellers transacting with various buyers.
Think of platforms like Amazon, Etsy, or Airbnb — they don’t just facilitate payments; they orchestrate the entire transaction lifecycle.
In this model, the marketplace owns the buyer relationship, manages disputes, and must also onboard, verify, and settle payments across multiple sellers.
It takes on responsibilities such as tax reporting, refund handling, and regulatory compliance across different markets.
Often, this setup requires split payouts, escrow mechanisms, and multi-party settlement workflows, making the backend significantly more complex.
To ensure trust and operational integrity, the marketplace must guarantee that:
-
Sellers are KYC/KYB verified
-
Buyers experience a consistent and seamless checkout
-
All government-mandated tax requirements are fulfilled
Key Differences Between Platform Payments and Marketplace Payments
Although they may look similar on the surface, the models diverge in structure and responsibility.
1. Control vs Facilitation
Platform payments simply facilitate money movement between a buyer and a single service provider. Marketplace payments must control and distribute funds across multiple sellers, making them more complex.
2. Ownership of Risk
In marketplace payments, the platform typically owns the liability — including fraud, chargebacks, or refund claims. In contrast, platform payments shift risk more toward the service provider or merchant.
3. Settlement and Flow of Funds
In platforms, payments often go directly to the seller after fees are deducted. In marketplaces, funds flow through the platform, then get split and routed to different sellers or service partners.
4. Compliance and Licensing
Marketplace payments may require money transmitter licenses, especially in the U.S., Europe, or Asia-Pacific. Platform payments may avoid this if structured carefully under PayFac-as-a-service or embedded finance models.
Compliance and Regulation in a Global Context
Here’s where it gets even more interesting — and where fintech leaders must tread carefully. The same platform structure may fall under different regulatory scrutiny across regions.
For example:
-
In the U.S., acting as a marketplace may classify your business as a money transmitter — requiring state-by-state licensing.
-
In Europe, under PSD2, marketplaces often fall under payment institution regulations if they control funds.
-
In India, the RBI mandates strict guidelines for payment aggregators and marketplaces collecting funds on behalf of sellers.
Platform payments often escape this complexity if they use third-party PayFacs like Stripe Connect, Adyen MarketPay, or Razorpay Route.
“Payments aren’t just about flow — they’re about accountability. Who touches the money, owns the risk.”
Mapping Your Model to the Right Risk Profile
So, how do you know which structure fits your business? Start by asking a few key questions. Are you enabling one seller or many? Will your system route funds between parties, or just facilitate the connection? Are you responsible for tax reporting, refunds, or escrow? Do you intend to own the buyer experience or remain in the background?
Your answers will directly shape your payment model, your licensing requirements, your legal risk, and your infrastructure decisions — especially as you scale across borders.
Hybrid Models Are Emerging — and Growing Fast
Interestingly, many global fintechs now operate hybrid structures — combining platform payments and marketplace features.
A great example is Shopify, which began as a platform for merchants but now offers marketplace-like features through Shopify Markets and Shopify Payments.
Similarly, event platforms like Eventbrite facilitate direct payments but also manage multi-seller events, edging into marketplace territory.
As embedded finance matures, expect these definitions to blur further, forcing regulators and fintechs to rethink licensing boundaries and risk-sharing structures.
Choosing the Right Infrastructure Provider
If you’re building a global payment flow, your infrastructure needs to match your business logic.
Look for providers that:
-
Offer modular tools for both platform and marketplace scenarios.
-
Support split payouts, multi-currency support, and global tax compliance.
-
Provide KYB/KYC onboarding for merchants and sub-merchants.
-
Deliver real-time dashboards, fraud detection, and developer-first APIs.
Global leaders like Stripe, Adyen, Rapyd, and Payoneer support both models — but each has different strengths in certain geographies and use cases.
Final Thoughts: The Model Defines the Risk, Not Just the Revenue
Understanding the core difference between platform payments and marketplace payments isn’t just a product decision — it’s a strategic one.
It affects your business classification, your customer experience, your legal obligations, and your funding readiness.
As the lines between software and finance blur, your choice of model must serve two goals: global compliance and user trust.
So the next time you’re integrating payments, don’t just ask what works — ask who owns the risk, who holds the funds, and who must stay compliant.
The answer will reveal whether you’re building a platform, a marketplace — or something the world hasn’t seen yet.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment