
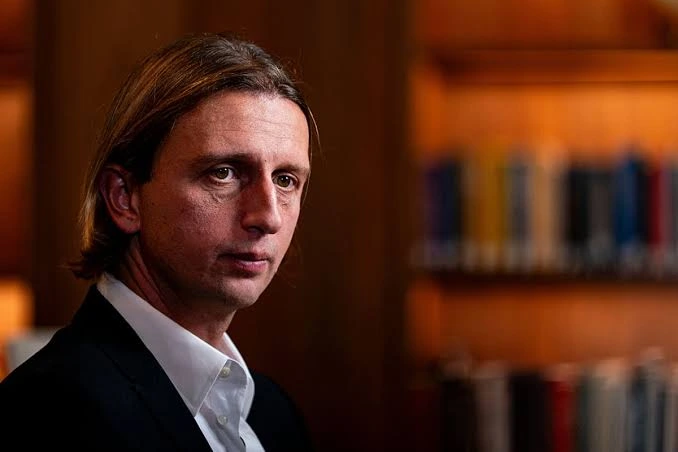
Revolut CEO Nik Storonsky has reiterated his preference for a US primary stock-market listing if the fintech eventually goes public, linking the potential move to the depth and liquidity of American capital markets. The comments, reported by Bloomberg on October 8, 2026, come as Revolut advances plans to establish a national bank in the United States and compete more directly with established financial institutions.
The company has not confirmed an initial public offering (IPO), a listing date, or a final exchange arrangement. A dual listing in London and New York had previously been discussed, while reporting has suggested that an IPO may remain several years away.
The shift in emphasis toward a US primary listing is nevertheless significant. Revolut is no longer positioning itself solely as a European fintech built around foreign exchange and international payments. It is seeking to expand its banking capabilities, deepen its presence in the American market, and build a broader global financial-services business.
Its ambitions are backed by a reported private valuation of $115 billion following a secondary share sale in 2026. However, turning that private-market standing into a successful public listing would require the company to demonstrate that its growth, profitability, risk controls, and expansion strategy can withstand the scrutiny of public-market investors.
Revolut CEO points to the depth of US capital markets.
In an interview with Bloomberg TV, Storonsky said a US primary listing had long been the target because of the depth of the American market.
The comments clarify his preference for a potential future offering, but they do not amount to a formal IPO announcement. Revolut remains privately held, and the company has not disclosed a final timetable or listing structure.
A primary listing establishes the principal market in which a company's shares are listed and traded. It can influence investor access, trading liquidity, market visibility, and the regulatory obligations associated with becoming a public company.
The United States offers access to large institutional investors, deep equity markets, and a substantial pool of capital focused on financial technology. For a company with global ambitions, a US listing could provide a platform for attracting investors who understand the economics of digital banking, payments, software, and technology-enabled financial services.
However, choosing a listing venue involves more than comparing market size. A company must consider valuation expectations, reporting obligations, governance standards, shareholder structure, compliance costs, and the long-term interests of existing investors.
Revolut would also need to assess how a US listing fits with its identity and operations in the United Kingdom and other markets. A preference expressed by its CEO is an important strategic signal, but the eventual decision would depend on the company's circumstances and market conditions at the time.
Why a US primary listing matters to Revolut
Revolut's American ambitions provide important context for Storonsky's comments.
The fintech has expanded from a business focused on foreign exchange and international money transfers into a wider financial services platform. Its offering has grown to include payments, cards, savings-related products, investments, and services for businesses, although availability varies by market and regulatory permissions.
The United States represents a substantial opportunity for a company seeking to expand these services. It is also a demanding market, with established banks, credit card issuers, payment networks, digital-first financial companies, and consumer technology platforms competing for customers.
A stronger American presence could help Revolut diversify its revenue sources and increase the reach of its products. It could also make the US more central to its long-term growth strategy, rather than treating the country simply as another market for international expansion.
A US primary listing would not automatically deliver those benefits. Public-market investors would still expect evidence that the company can acquire customers efficiently, encourage them to use more products, generate sustainable profits, and manage risks across multiple jurisdictions.
For Revolut, therefore, the listing preference and the banking strategy are connected. Building a stronger operating business in the United States could support the case it eventually presents to investors. Equally, a successful listing would depend on more than a compelling growth narrative.
US national bank charter advances, but final approval remains outstanding
A central development in Revolut's US strategy came on September 2, 2026, when the Office of the Comptroller of the Currency (OCC) conditionally approved its application to establish Revolut Bank US, National Association.
The decision represents an important regulatory milestone, but conditional approval is not the same as final authorization to commence full banking operations.
According to Revolut's September announcement, the company must continue working through remaining requirements involving the Federal Deposit Insurance Corporation (FDIC), the Federal Reserve, and final OCC approval. It has outlined a planned launch in 2027, subject to the necessary regulatory steps.
The distinction matters because a national bank charter can provide a framework for a broader range of banking services, but a company cannot assume that every proposed product becomes available as soon as conditional approval is granted.
Revolut has said the proposed US bank would support its plans to offer services including credit cards and loans. Those plans remain dependent on the relevant approvals, operational readiness, and applicable requirements.
A full US banking operation could also allow Revolut to build a more integrated customer experience and reduce its reliance on arrangements needed to provide certain services through third parties. The precise capabilities available at launch will depend on the final regulatory position and the products the bank is authorized and prepared to offer.
The OCC's decision therefore strengthens Revolut's expansion prospects without eliminating the execution risk. The next milestones will be the completion of outstanding regulatory conditions, final authorization, and the transition from preparation to operating services.
Revolut's $115 billion valuation raises the stakes.
Revolut's reported $115 billion valuation provides another reason its potential IPO strategy is attracting attention.
The valuation followed a secondary share sale in 2026. Secondary transactions allow existing shareholders, including employees in some arrangements, to sell shares to investors. They differ from an IPO, in which a company enters public markets through a formal offering and listing process.
The distinction is essential. A private transaction establishes a valuation based on the terms of that transaction, the shares involved, and investor demand at that time. It does not guarantee that public-market investors would value the business at the same level.
A public offering would expose Revolut to a different set of market dynamics. Investors would scrutinize its financial statements, revenue composition, profitability, customer activity, competitive position, capital requirements, and regulatory risks. Market conditions could also affect both the timing of an offering and the price investors are willing to pay.
The $115 billion figure nevertheless highlights the scale of Revolut's development. Reuters has reported that the valuation places the company above the market value of several major European banks, including Barclays and Société Générale, at the time of reporting.
Comparisons between a private fintech valuation and the market capitalization of established banks should be treated carefully. Traditional banks and technology-led financial platforms can have different revenue mixes, lending exposures, capital requirements, and risk profiles. Their headline valuations do not, on their own, establish which business model is stronger.
For a future IPO, the central question would be whether Revolut can convert its customer growth and expanding product range into durable financial performance while maintaining the controls expected of a large financial institution.
From customer growth to a global financial platform
Revolut's expansion strategy is built around increasing its customer base and entering more markets. In its May 2026 customer update, the company said it had surpassed 70 million customers globally and was working toward 100 million by mid-2027. Subsequent reporting in October put its customer base above 80 million.
These milestones demonstrate substantial growth, but the 100-million figure remains a company target rather than an achieved result. Likewise, a goal of operating in 100 countries should not be confused with current coverage.
Expanding across jurisdictions presents operational challenges. Each market can involve different licensing requirements, consumer-protection rules, payment systems, financial-crime controls, and expectations for customer support. Products that are available in one country may not be available in another.
Revolut's ambition is to build a financial platform that can serve customers across borders while adapting its products and compliance arrangements to local requirements. That approach could create opportunities to cross-sell services and generate more revenue from existing customers.
Yet customer numbers alone do not show how deeply users rely on a provider. Investors will also want to understand active usage, primary-account adoption, customer retention, product engagement, and the profitability of individual markets.
For Revolut, moving from a large digital customer base to a comprehensive banking relationship is an important part of its next stage. The US banking initiative could contribute to that shift if the company secures the necessary approvals and develops products that compete effectively with local alternatives.
Competing with established US financial institutions
Storonsky has described the US ambition in expansive terms, identifying major institutions such as JPMorgan Chase and American Express as competitors Revolut wants to challenge.
The comparison reflects a broad competitive objective rather than equivalence between the businesses. JPMorgan operates a large diversified banking franchise, while American Express has a distinct card and payments model. Revolut's product mix, geographic reach and maturity differ from both.
Nevertheless, the competitive pressure is real. American consumers can choose from large national banks, specialist card issuers, online banks, payment apps and financial technology platforms. A digital interface and rapid product development may help attract customers, but they do not remove the need for reliable service, fraud prevention, sound underwriting and regulatory compliance.
Credit cards and lending could become important parts of Revolut's US offering if its proposed bank receives final authorisation and the company proceeds with those products. Lending can create interest income and deepen customer relationships, but it also introduces credit risk, underwriting requirements, funding considerations and potential losses when borrowers fail to repay.
The challenge is to balance growth with risk management. Expanding into lending may increase the range of services Revolut can provide, but the business would need to establish suitable controls and demonstrate that the economics work across different customer segments.
Competition also extends beyond products. Trust, customer service, fraud handling and transparency can influence whether customers use a digital provider as their main financial institution or only for selected transactions.
That makes execution particularly important. Revolut's US ambitions will be judged not only by how many customers it attracts, but by the reliability and breadth of the relationships it builds.
AI could broaden Revolut's ambitions beyond banking
Revolut's strategy also includes artificial intelligence and a wider technology agenda.
In April 2026, the company announced AIR, an in-app AI assistant designed to help customers understand their finances, review spending, manage subscriptions and carry out selected tasks through conversational interaction. The initial rollout was announced for customers in the United Kingdom.
The launch illustrates how Revolut is attempting to integrate AI into its existing financial-services platform. Rather than requiring users to navigate multiple menus, a conversational assistant can provide another way to access information and supported functions.
The wider industry is exploring how AI could improve customer support, financial insights, fraud detection and the delivery of personalised services. These applications could reduce friction for customers and help financial companies make better use of the information generated by everyday transactions.
However, an AI assistant is not the same as a fully autonomous shopping agent. The latter would involve an AI system carrying out more steps in a purchasing process, potentially including product discovery, comparisons and transactions. Such capabilities raise additional questions about authorisation, payment security, consumer consent and responsibility for errors.
Although recent reporting has discussed Revolut's broader AI ambitions, the specific timing and initial market for a planned autonomous-shopping test could not be independently established from the available official material. Those details should not be treated as confirmed.
For the moment, AIR's announced financial-assistant functionality offers a verified example of Revolut's AI direction. The longer-term commercial opportunity will depend on how useful these tools become, how safely they handle sensitive financial interactions and whether customers trust them with increasingly consequential tasks.
The challenges behind Revolut's growth story
Revolut's scale and valuation do not remove the challenges associated with expansion.
Operating across multiple markets requires strong financial-crime controls, customer protection, data security and regulatory oversight. A broader banking footprint can increase the range of products available to customers, but it can also increase the complexity of managing risk.
Recent reporting has highlighted regulatory and data-security issues affecting the company. In 2025, Lithuania's central bank fined Revolut's banking entity €3.5 million over deficiencies related to transaction monitoring. In October 2026, Reuters also reported an incident involving the disclosure of personal data belonging to hundreds of customers following a deceptive request connected to an unused email address associated with an Italian government agency.
These reports are relevant to the company's expansion story because trust and control frameworks are important to both regulators and investors. They should not, however, be treated as proof that every part of Revolut's systems failed or that a proposed US bank will necessarily face the same issues.
A potential IPO would bring its own demands. Public shareholders typically expect consistent disclosures, clear governance, transparent risk reporting and a credible explanation of how management plans to sustain growth. A larger customer base and higher valuation increase the significance of these expectations.
Revolut must therefore demonstrate that its operating controls can scale alongside its products and geographic footprint. Strong execution in this area could support its expansion strategy; weaknesses could undermine customer confidence and complicate regulatory progress.
What to watch next
Several developments will help determine whether Revolut's US ambitions translate into a public-market opportunity.
First, investors will watch the regulatory process for the proposed national bank, including outstanding FDIC and Federal Reserve requirements and final OCC authorisation. The planned 2027 launch remains conditional on progress through these steps.
Second, the company will need to clarify how it intends to structure any future IPO. A US primary listing is Storonsky's stated preference, while a dual listing has previously been discussed. Neither should be presented as a settled arrangement until Revolut confirms its plans.
Third, financial performance will remain central. Customer growth, product adoption, revenue diversification and profitability will help determine whether the business can support its valuation in a public-market setting.
Finally, investors will monitor the company's ability to expand its AI capabilities responsibly and maintain strong risk controls as its services become more sophisticated.
Conclusion: Revolut's US ambitions go beyond an IPO
Storonsky's preference for a US primary listing is a clear signal of where Revolut sees strategic opportunity. The American market offers deep capital pools, a large customer base and the possibility of building a more comprehensive banking business.
But a listing remains a future possibility, not a confirmed event. The $115 billion valuation reflects a private share transaction, while the proposed US bank still requires further regulatory progress before it can begin full operations as planned.
The next stage will depend on whether Revolut can turn its scale and technology-led model into a durable, trusted financial-services business in the United States. For investors and the wider fintech industry, the key story is not simply where Revolut might list its shares. It is whether the company can build the operating strength, regulatory foundations and financial performance needed to compete at that level.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment