
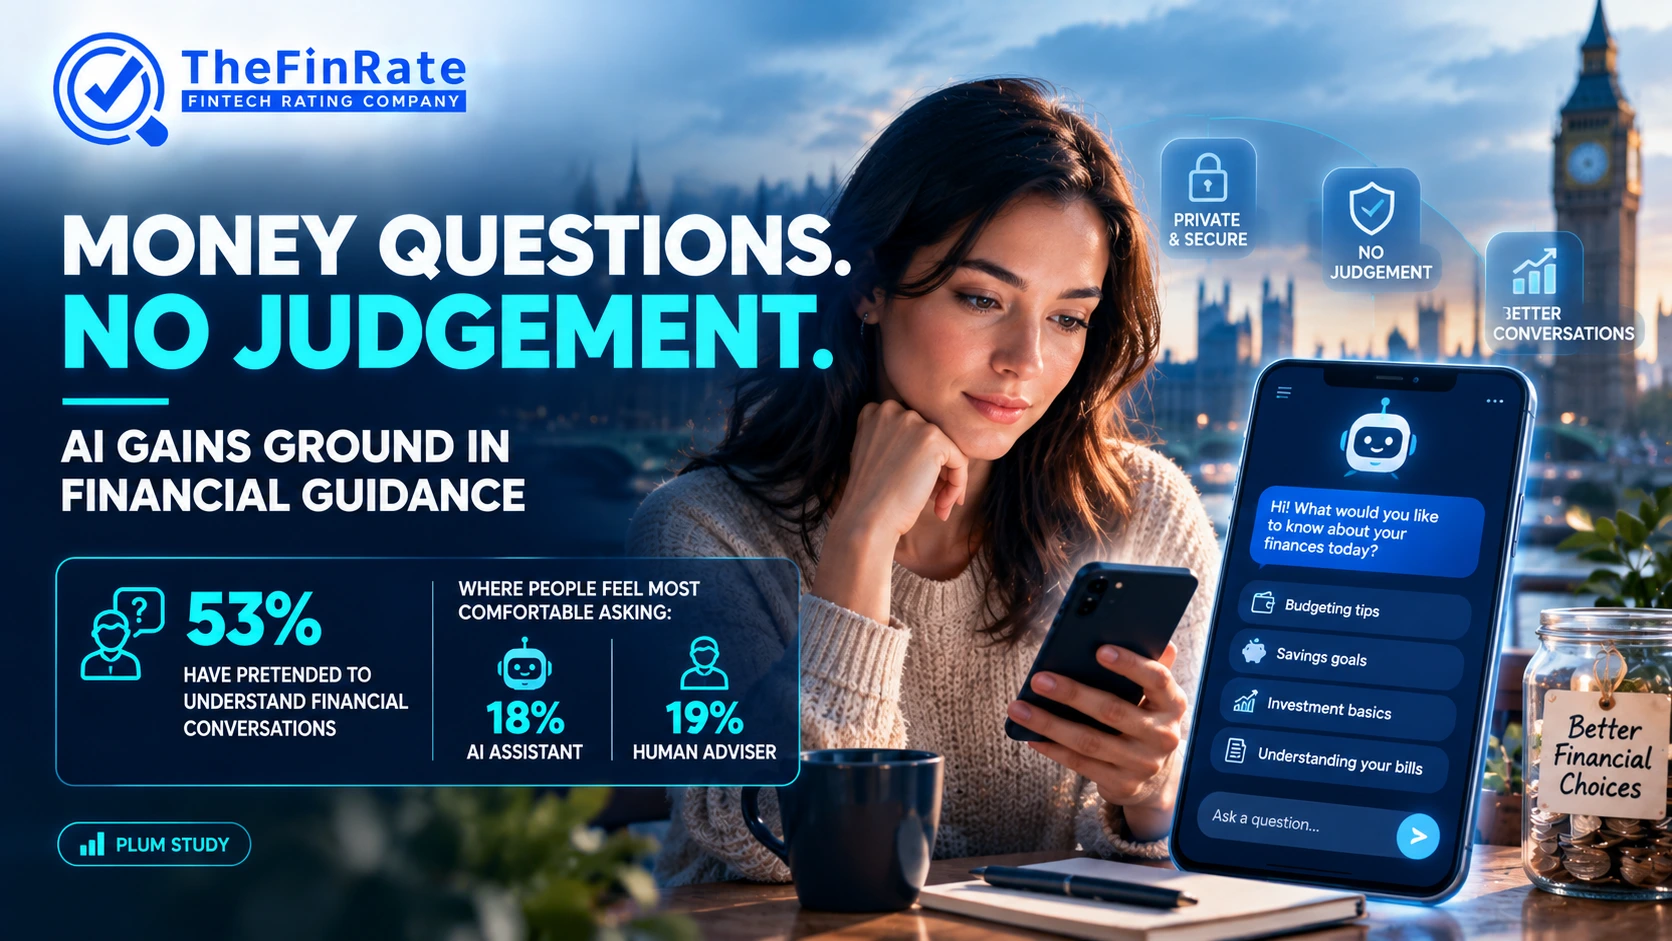
UK consumers are increasingly looking to artificial intelligence for financial guidance. Embarrassment and fear of judgement are emerging as barriers to asking questions about money, according to new research from banking app Plum. AI assistants could help ease this discomfort by offering a private space to explore financial topics, the study suggests.
The research found that 35% of respondents avoid asking more questions about their finances because they fear sounding unintelligent. More than half, or 53%, said they had pretended to understand a financial conversation. Meanwhile, 42% said they would ask more questions if they knew they would not be judged.
The findings point to a challenge that goes beyond access to information. Even when advice and educational resources are available, consumers may hesitate to use them if they feel uncomfortable admitting they do not understand a concept.
That hesitation may explain why AI assistants are becoming appealing. In Plum's survey, 18% said they would feel most comfortable approaching an AI assistant with a financial question, close to the 19% who preferred a human adviser. For banks and fintech companies, the results highlight an opportunity to make guidance more approachable, while also raising questions about reliability and when a question needs qualified human advice.
Fear of Judgement Remains a Barrier to Financial Understanding
Financial literacy is not simply about knowing how interest rates or investments work. It also means feeling confident enough to ask questions before making a decision. The Plum findings suggest that confidence is missing for some consumers, who may choose to stay silent rather than admit they need help.
Pretending to understand a conversation carries consequences. A consumer who does not grasp a loan's terms or an investment's risks may leave without the knowledge needed to decide well. The survey does not prove embarrassment directly causes poor outcomes, but it identifies a real obstacle: people cannot close gaps in their knowledge if they will not acknowledge them.
The issue matters for institutions too. Banks may offer detailed product information, but it helps less if customers feel uncomfortable asking follow-up questions. A more accessible approach could bridge that gap through tools that explain unfamiliar terms in plain language.
AI Assistants Are Closing the Gap With Human Financial Advisers
One of the study's most notable findings concerns the type of support consumers feel most comfortable approaching. According to Plum, 18% would feel most comfortable asking an AI assistant, compared with 19% who prefer a human adviser. The gap is small, but it shows how AI is becoming a real consideration in the search for financial guidance, with some people drawn to the privacy of digital assistance.
AI assistants can explain terminology, summarize complex information, and answer repeated questions without making users feel judged. These features may help people just beginning to learn about budgeting, saving, or investing, letting them ask a question in everyday language rather than arranging an appointment.
However, the survey measures stated preferences, not the accuracy of AI advice or the quality of decisions made afterward. The results read as a signal that AI could become an additional route for financial information, not proof it is replacing human advisers.
Why Privacy and Accessibility Matter in Personal Finance
Money can be a sensitive subject. Consumers may feel embarrassed about debt, low savings, or uncertainty about financial products. An AI assistant may lower the barrier to asking questions, since users can seek explanations privately without worrying about an immediate reaction.
Will Bryant, Director of Wealth Strategy at Plum, said money can feel difficult to discuss because people often believe they are expected to already know the answers. Asking questions privately, without fear of judgement, removes some of those barriers, he suggested, pointing to a role for AI in financial education.
Privacy, though, should not be assumed just because a conversation happens with an AI assistant. Users still need to understand how a service handles personal data and whether conversations improve its systems. Providers will need clear data practices to build trust.
Social Media Ranks Lowest for Financial Guidance
The survey also asked how comfortable respondents would feel approaching different sources for financial help. Social media ranked lowest, with just 1% selecting it, a notable result given the visibility of "finfluencers" on social platforms.
Content quality on social media varies widely, and users may struggle to separate genuine education from promotional material. The figures describe comfort, not each channel's actual effectiveness, but they reinforce the value of guidance people find credible.
What the Findings Mean for Banks and Fintech Companies
For financial institutions, the challenge is not simply adding AI to an app. It is understanding what customers need from guidance and how technology can deliver it.
Conversational tools can explain unfamiliar terms in plain language and adapt when users need more detail. They also make follow-up questions easier, since an assistant lets customers ask the same question in different ways without feeling they are repeating themselves to a person. Such tools can direct customers to relevant account details or product terms too, though personalized guidance needs to rest on suitable data and clear limitations. Finally, they can flag when human support is necessary, since complex investment decisions and serious debt difficulties may require a trained adviser.
These opportunities bring responsibilities as well. Institutions must weigh inaccurate responses, misleading confidence, and the risk that customers read general information as personalized advice. A good AI assistant should communicate uncertainty and point customers to appropriate support when a question exceeds its scope.
Accessibility Must Be Matched by Accuracy
Making financial conversations more comfortable is valuable, but accessibility alone is not enough. AI systems can produce incomplete explanations or present uncertain information with unwarranted confidence, which carries real consequences if consumers rely on a flawed answer when borrowing or investing.
Providers should design assistants around clear boundaries: distinguishing general education from regulated advice, protecting customer data, and making it easy to reach a human when needed. Not every customer is equally comfortable with AI, so offering several routes to support serves people with different needs.
The Plum study does not prove AI improves financial literacy. It does suggest that willingness to seek help depends on how comfortable people feel asking questions, a useful consideration for providers building the next generation of digital financial services.
The Bottom Line
Plum's research highlights a human factor behind the growing interest in AI-powered financial guidance: consumers may want a place to ask questions without feeling embarrassed. With 35% reluctant to ask more questions for fear of sounding unintelligent, and 53% admitting they have pretended to understand a financial conversation, the findings point to a gap between the information available and people's confidence in using it.
AI assistants could help close that gap by making explanations more conversational and private. But success should not be measured by adoption alone. Accuracy, privacy, and access to human expertise remain essential if these tools are to support better financial decisions. For banks and fintech companies, the opportunity is to use AI not just to automate interactions but to make financial understanding easier to reach.
Lack of financial confidence driving consumers to AI assistants
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment