
Introduction
In today’s world of rapid tech disruption and heightened expectations on sustainability, companies that successfully weave technology with purpose are reshaping entire industries. One such example is Fuse Energy, a UK-based energy technology company founded by former Revolut executives that has rapidly grown — hitting a $5 billion valuation amid $70 million in funding — by rethinking the traditional energy model through technology, operational integration, and sustainable incentives.
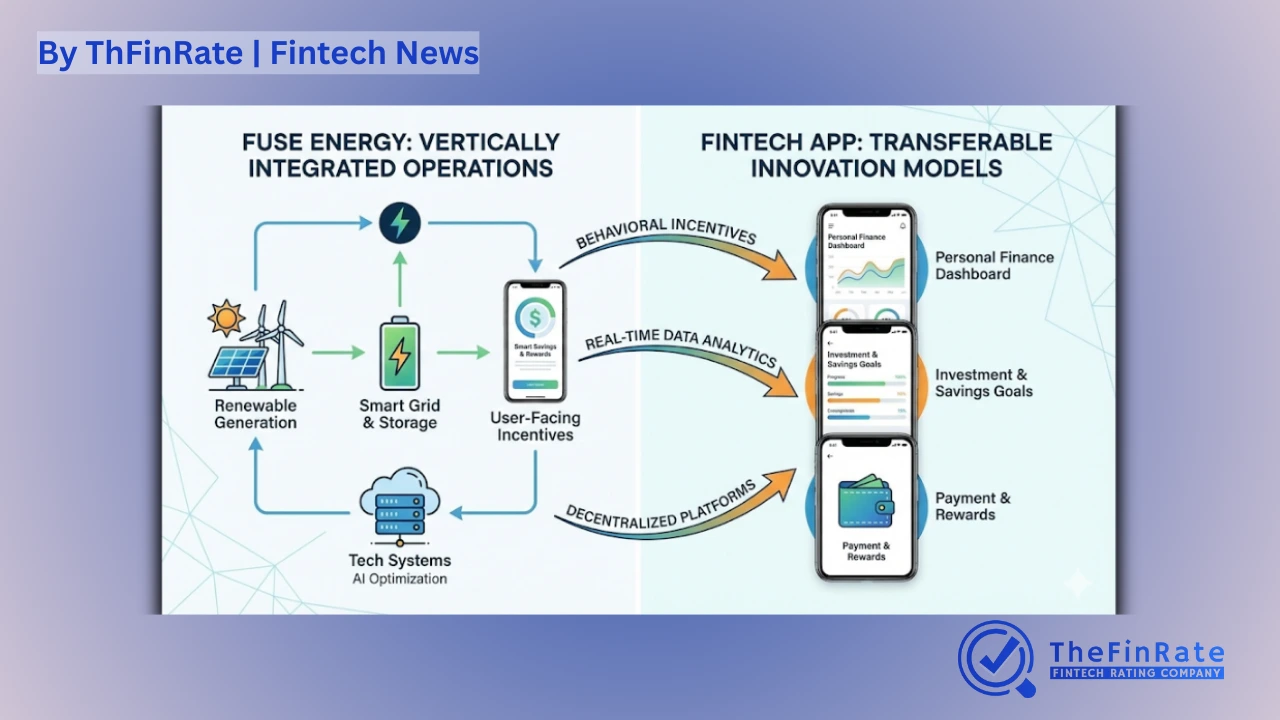
Although Fuse Energy isn’t a fintech firm, its strategic fusion of technology, customer engagement and sustainability offers clear lessons for fintech founders and investors. By looking at how Fuse integrates vertical control, real-time data systems, incentive frameworks and practical blockchain use, fintech startups can find inspiration for scaling their own platforms more effectively.
Fuse Energy: A Brief Snapshot
Founded in 2022 by ex-Revolut executives Alan Chang and Charles Orr, Fuse Energy has taken on an entrenched incumbency — the energy utilities sector — by building a vertically integrated, tech-enabled platform that owns everything from renewable generation and grid management to end customer delivery.
Unlike legacy providers that typically operate fragmented supply chains, Fuse’s model cuts out the middleman and leverages incentives, software and hardware integration to deliver lower prices (about 10% below incumbents) and energy services optimized for user needs.
This focus on tech-led operations and sustainability provides several transferable lessons for fintechs — particularly those aiming to build resilient, meaningful, and customer-centric products.
1. Vertical Integration Can Boost Margins and Control
Fuse Energy deliberately built control over the entire value chain — from renewable site construction to energy trading and delivery — allowing it to reduce costs and improve service performance.
What Fintech Can Learn
For fintech startups, vertical integration doesn’t have to mean owning every component of the financial stack, but reducing reliance on third parties for critical functions — such as payment processing, data infrastructure, or compliance workflows — can meaningfully improve margins and customer experience.
This could manifest as:
- Building native payment rails or deeper API control
- Bringing compliance tooling in-house to reduce third-party costs
- Owning more of the data infrastructure to support analytics and risk modeling
Like Fuse’s energy model, stronger upstream control can translate into faster innovation cycles and tighter cost management.
2. Align Tech With Real-World Operations
Fuse pairs hardware (solar, batteries, EV chargers) with software systems that provide real-time monitoring and optimization of grid interactions.
What Fintech Can Learn
Fintech startups often embed tech superficially — for instance, wrapping an app around legacy backend systems. Fuse shows that true impact comes when technology directly enhances operational execution.
Fintech examples might include:
- Integrating real-time risk monitoring directly into underwriting engines
- Coordinating digital core banking with customer behavior data
- Using real-time insights to dynamically adjust pricing, credit limits, or rewards
In other words, tech should enable operational excellence, not just surface it.
3. Use User Incentives to Drive Engagement
One hallmark of Fuse Energy’s model is its token-based incentive system — the $ENERGY token — which rewards users for grid-friendly behaviors, such as shifting energy use to times of lower demand.
What Fintech Can Learn
Reward systems are nothing new in fintech (think cashback, points, and tiered benefits), but Fuse’s model ties rewards to real-world behavior that furthers company goals — a lesson fintech can adapt by:
- Rewarding financially healthy behavior (e.g., saving, early repayment)
- Aligning incentives with ecosystem outcomes (e.g., reduced overdraft use)
- Tokenizing rewards in a way that reflects contribution and engagement
Importantly, Fuse’s token incentives recently gained regulatory clarity from the U.S. SEC, reinforcing that incentive programs can be structured in compliance with financial regulations.
4. Blockchain Should Support Operations, Not Drive Them
While Fuse uses blockchain for incentives and settlements, its core business doesn’t rely on blockchain as the primary product model. Instead, blockchain is used practically and incrementally to settle rewards and coordinate on-chain interactions.
What Fintech Can Learn
Many fintechs mistakenly center blockchain as a differentiator rather than a tool. Fuse’s approach demonstrates that:
- Blockchain can enhance settlement, transparency, or tokenization without complicating core business logic
- Projects should evaluate where blockchain delivers real utility — not just adopt it for novelty
- A hybrid approach — combining centralized operational systems with blockchain where appropriate — often works best
This measured use of blockchain can reduce complexity, cost, and regulatory friction for fintech startups.
5. Partnerships Expand Reach Without Full Buildout
Fuse Energy has pursued strategic partnerships — for example, with EV charging networks and carbon credit ecosystems — to broaden its market without having to build every capability internally.
What Fintech Can Learn
Partnerships remain a powerful growth lever in fintech:
- Collaborate with established banks for regulated banking rails
- Team up with payroll platforms to offer embedded finance
- Integrate with B2B SaaS solutions to offer embedded payments or lending
The right partnerships allow fintechs to scale reach and offerings without burdening their development roadmap or capital.
6. Combating Market Gaps Through Inclusion
Fuse also leverages on-chain systems to expand access to energy markets that may have been inefficient or inaccessible — a parallel to financial inclusion goals in fintech.
What Fintech Can Learn
Fintech’s original promise was to bring financial services to the unbanked and underserved. Fuse’s model reinforces this by:
- Reducing barriers to participation (real-time incentives, token rewards)
- Using tech to reach customers beyond traditional networks
- Delivering transparency in pricing and value
Fintech startups can adopt similar principles to design products that inherently increase access and deliver measurable user empowerment.
Conclusion
While Fuse Energy sits squarely in the energy sector, its strategic marriage of technology, vertical control, customer engagement and practical blockchain use offers valuable insights for fintech startups. The core lessons — from aligning technology with business operations, to thoughtful use of incentives, to partnership-led scaling — all underscore that innovative business models can come from outside an industry, yet be deeply relevant within it.
Fintech startups that incorporate these principles into their own product and growth strategies will be better positioned to navigate competitive pressures, accelerate adoption, and deliver value that resonates with users and investors alike.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment