
Swedish fintech startup Matters has come out of stealth with $5 million in pre-seed funding. It plans to build an AI-native personal finance platform that changes how consumers manage money and how banks earn revenue.
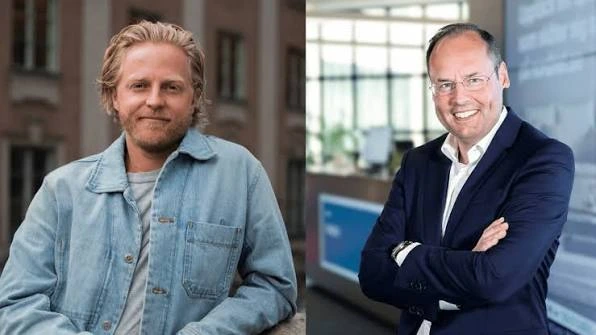
Founder Per Österström, who also built consumer loan broker Sambla Group, leads the company. Matters is developing a digital banking service with three parts: an AI financial adviser, a flat monthly subscription, and a cashback model that returns selected transaction-related revenue to customers.
Swedish angel investor Jakob Johansson led the round. Knut Frängsmyr, former chief operating officer of Klarna, joined it, along with other angels tied to Voi, Röko, Validio, and Evoke. The company has also named Lars-Åke Norling, former chief executive of Nordnet, as chair.
A different business model for digital banking
Most digital banks compete on low fees, slick apps, and budgeting tools. Matters takes a clearer stance on how its revenue relates to customer outcomes. Customers would pay a flat monthly fee. Revenue that banks usually keep from transactions, such as interchange and foreign exchange fees, would go back to customers as accumulated cashback.
Interchange fees are generally paid by a merchant’s payment provider to the cardholder’s issuing bank on each card transaction. Foreign exchange fees arise when a payment involves currency conversion. The amount Matters can return will vary with customer activity, pricing, and product terms.
The subscription gives the business a direct revenue stream. The cashback aims to make the value exchange more visible. Yet the launch announcement leaves key details open. It does not give subscription prices, cashback rates, eligibility rules, payment-provider arrangements, or the full list of services in the first product. Those numbers will decide whether the model can reward customers and still cover compliance, technology, and operating costs.
How the AI adviser is meant to work
Matters is building an AI adviser to help customers understand their spending, save more, and work toward their goals. The idea goes beyond showing balances or sorting transactions. Such a tool can use spending patterns and user goals to flag recurring costs, spot late-fee risks, or compare spending against a budget.
The founder has described an assistant that could find forgotten subscriptions and locate cheaper travel options. Those are goals, not confirmed features. The product’s value will depend on the quality of its advice. It must separate spending a user wants to cut from spending that covers essentials or personal priorities. It must also handle data securely and explain its suggestions. And it should never present an uncertain recommendation as a guarantee.
AI sits at the center of the plan here. It is not a chat layer on top of ordinary banking. Still, a good conversation is not proof of value. The real test is whether customers use the adviser consistently and make better decisions because of it.
What sets Matters apart, and what is unproven?
The model combines subscription revenue, AI guidance, and cashback. A subscription builds a direct link between service and customer. The adviser makes money management more proactive. Cashback returns part of the transaction revenue. This mix could appeal to people who want more help but will not pay for traditional wealth management.
The model also faces real hurdles:
- Pricing: A flat fee must attract users without making the service uneconomic.
- Cashback: It must be funded transparently, and benefits will shift with payment activity.
- Trust: The adviser must give reliable, relevant guidance that users understand.
- Competition: Digital banks and finance apps already offer spending analytics, savings tools, and automated insights.
Matters will need to show a clear improvement over those rivals. Using AI alone will not be enough.
Funding for licensing and expansion
The $5 million gives Matter's capital to build its product, pursue regulatory permissions, and prepare for a wider European launch. The company says it intends to apply for the licenses its banking plans require. Raising money does not mean it already holds them. The permissions it needs will depend on the services it offers and the countries where it operates.
European expansion means dealing with national regulators, EU financial rules, consumer-protection duties, payment requirements, and data-protection standards. If Matters works through licensed partners, those arrangements and their responsibilities will matter too.
The company starts with a 14-person team and plans to hire as it builds. It is also weighing strategic acquisitions, though it has announced no deal. Acquisitions could bring technology, talent, or customers. They could also add complexity, so tight capital discipline will matter at this stage.
Leadership and investors
Österström’s background in Nordic consumer lending gives the startup a base in household financial decisions. Norling adds experience from Europe’s savings and investment market. The investor group reported in the funding announcement includes
- Knut Frängsmyr, former Klarna COO
- Douglas Stark, co-founder of Voi
- Johan Bladh, CEO of Röko
- Patrik Tran, CEO of Validio
- Per Widerström, CEO of Evoke
That mix of consumer-finance and tech experience could help with product design and the demands of regulated services. Long-term success will still depend on the product, customer trust, and financial results.
AI moves into everyday money management.
Fintech firms are applying AI to tasks that once took manual effort or specialist help. In personal finance, that includes spotting spending patterns, summarizing transactions, finding subscriptions, and setting budgets. These tools could help people who struggle to track expenses.
Access to an AI adviser does not guarantee better outcomes, though. Advice must be accurate and fit each user. Privacy matters just as much. A platform that offers personal guidance needs sensitive data on income and spending, so users need clarity on how it is collected, processed, and shared.
Regulation adds another layer. Helping customers understand their finances is different from giving regulated financial advice. The treatment depends on the actual services offered, not on whether AI is involved.
What to watch next
Several milestones will show whether Matters can turn its concept into a business:
- Product launch: which features arrive first and how they perform
- Regulatory permissions: the licenses or partnerships it secures
- Subscription value: whether customers see the fee as worth it against free alternatives
- Cashback transparency: how it is calculated and explained
- AI results: whether the adviser helps users reach their goals
- Retention: whether customers keep paying after the launch period
- European rollout: how it handles differences between markets
The bottom line
Matters wants a bank whose revenue grows when customers manage money well. The idea is promising, but questions remain on pricing, licensing, product quality, and the economics of sharing revenue. The company must show it can deliver lasting value and a sustainable business.
For the wider industry, the launch reflects a shift in ambition. Fintech is moving from digitizing banking toward using AI to make personal finance proactive and personal. Matters’ first product will show whether it can deliver on that promise.
AI-native personal finance platform Matters emerges from stealth with $5M pre-seed
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment