
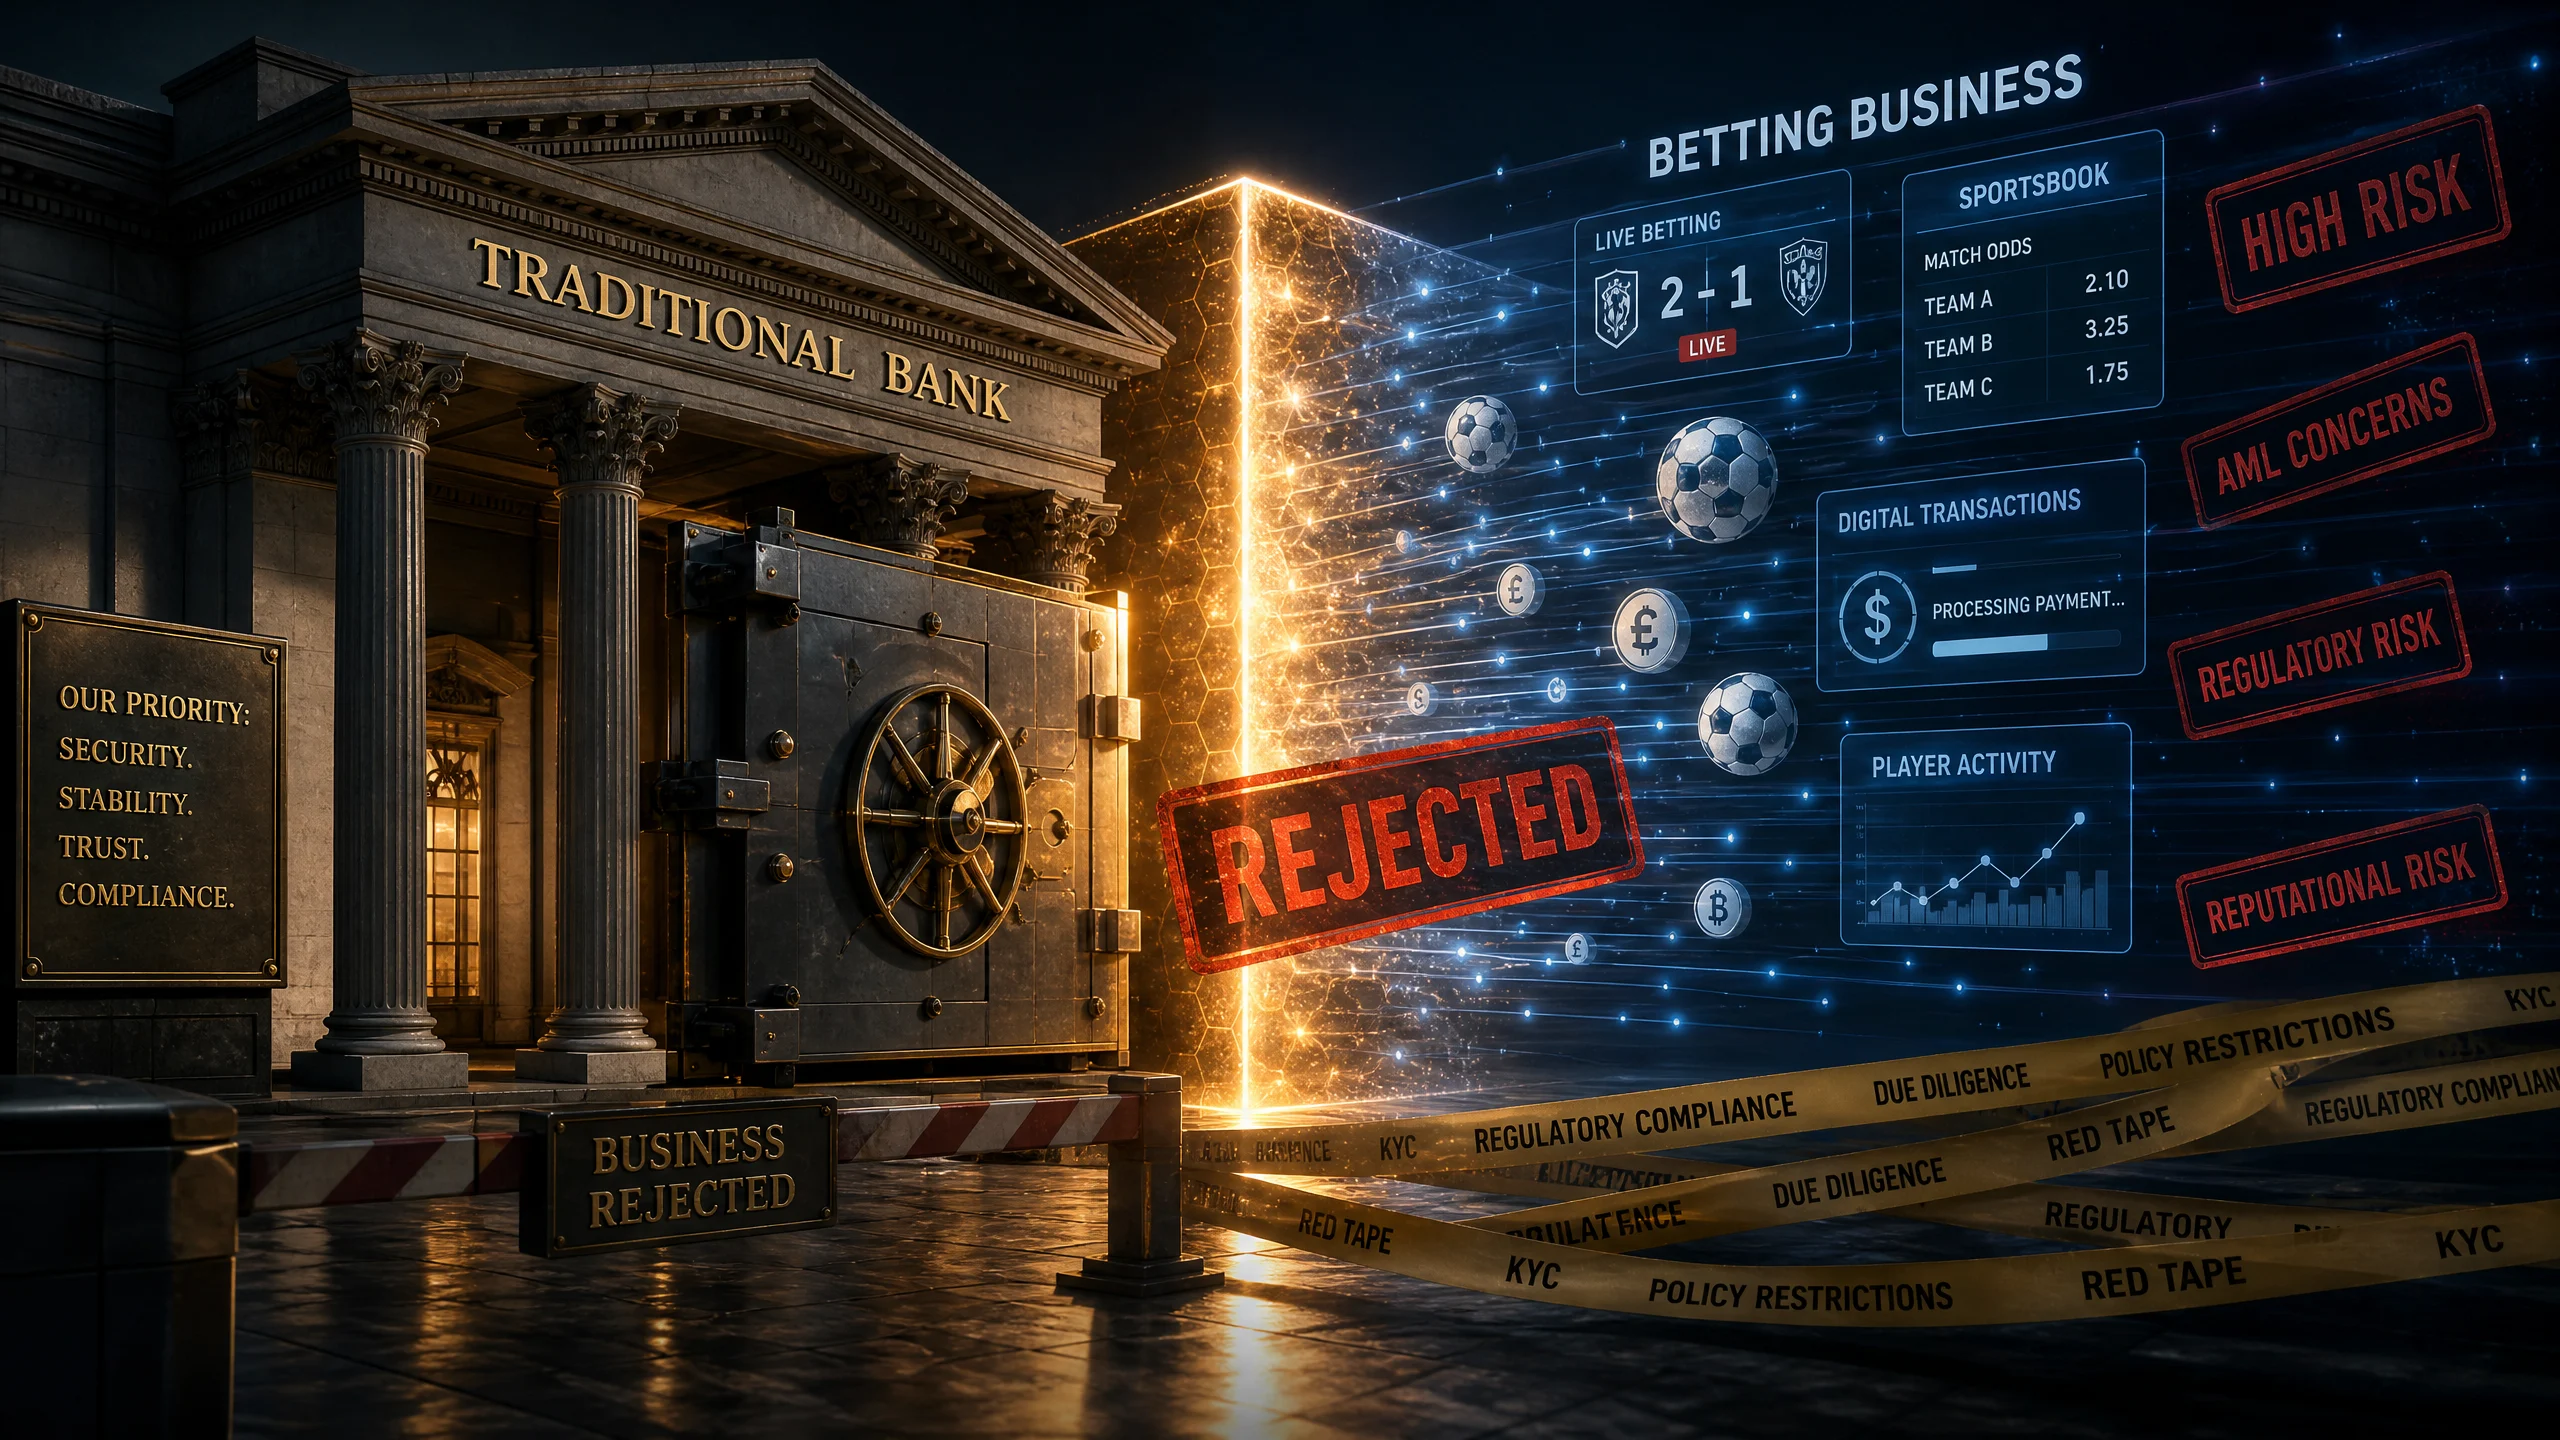
A properly licensed sportsbook operator, with clean books and a genuine compliance program, can still get turned away by three banks in a row, not because of anything the business did wrong, but because of how banks manage risk at the portfolio level. This is one of the most persistent frustrations in the betting industry, and it’s worth understanding the actual mechanics behind it, because the reasons are more structural than most operators assume, and a genuinely significant regulatory shift in 2026 has started changing part of the picture.
The Core Mechanism: De-Risking, Not Individual Judgment
What De-Risking Actually Means
De-risking is the practice of banks restricting or terminating entire categories of business relationships, rather than assessing and managing risk merchant-by-merchant, when the compliance cost of adequately managing that category’s risk profile is judged to outweigh the relationship’s value. This is a portfolio-level decision, not a verdict on any specific betting operator’s individual quality or compliance standing.
Why This Happens Structurally
Banks apply a risk-based approach, grounded in FATF international standards and regional regulatory guidance (like the European Banking Authority’s), assessing not just a business’s financial standing but its industry, geography, ownership structure, transactional behavior, source of funds, and reputation. Online gambling and betting sit among the sectors regulators explicitly flag as carrying some of the highest money-laundering and terrorist-financing risk, a classification that shapes how cautiously banks treat the entire category before any individual underwriting even begins.
Once a business is flagged high-risk, it requires enhanced due diligence (EDD), a genuinely more intensive and costly compliance process than standard onboarding. Financial institutions weighing that added cost against the relationship’s profitability frequently conclude the math doesn’t work, particularly for smaller or newer betting operators without an established track record justifying the extra compliance investment.
The Specific Risk Factors Banks Weigh
Elevated Chargeback and Dispute Volume
Industries with large volumes of online payments, gambling, adult entertainment, and other digital services, traditionally face significantly more returns and disputed transactions than typical retail categories. For banks, this signals instability and additional financial risk, independent of whether any individual operator’s actual dispute rate is well-managed.
Complex or Offshore Ownership Structures
Many betting operators, particularly those licensed through offshore jurisdictions (covered in depth in our companion guide on offshore versus local betting licenses), have layered or international ownership structures. If a bank can’t clearly identify the ultimate beneficial owners (UBOs) behind an operator, that’s automatically treated as a red flag during underwriting, regardless of whether the underlying ownership is entirely legitimate.
Correspondent Banking Exposure
For betting operators processing internationally, correspondent banking relationships add another layer of risk banks have to manage. Concerns about AML and customer due diligence compliance have led many large international banks to pull back from correspondent relationships with smaller banks in jurisdictions viewed as higher-risk, a dynamic the Bank for International Settlements has directly linked to rising compliance costs and uncertainty about how far due diligence needs to go to avoid regulatory sanction. A betting operator relying on cross-border payments infrastructure through a correspondent chain inherits this exposure indirectly, even when the operator’s own compliance program is genuinely strong.
Reputational Sensitivity
Sectors like online gaming, adult content, and CBD have historically been treated by banks as reputationally sensitive, meaning banks weighed not just legal compliance, but potential negative media coverage, public opinion, and shareholder reaction to the relationship. This reputational dimension, discussed further below, is exactly the piece that changed meaningfully in 2026.
Regulatory Fragmentation Across Jurisdictions
Banks operating across multiple jurisdictions have to navigate genuinely complicated, sometimes conflicting international compliance rules, and even small mistakes in that navigation can lead to serious regulatory penalties. Banks tend toward extra caution specifically because the downside of getting this wrong (fines, regulatory action) is asymmetric compared to the upside of banking any individual high-risk merchant relationship.
What Changed in 2026: The End of “Reputational Risk” as Justification
This is a genuinely significant, recent shift worth understanding in detail, since it directly addresses part of why betting businesses have historically struggled with banking access.
The Regulatory Change
In 2026, US banking regulators finalized a rule eliminating reputational risk as a standalone justification banks can use for closing accounts or terminating relationships. The rule specifically bars agencies from requiring, instructing, or encouraging institutions to close accounts based on a customer’s political, social, cultural, or religious views, constitutionally protected speech, or involvement in “politically disfavored but lawful business activities perceived to present reputation risk.”
What This Does – and Doesn’t – Change for Betting Operators
What it changes: Banks can no longer point to pure reputational concern, “we don’t want to be seen banking a gambling business”, as sufficient grounds for account closure on its own. Account closures now need to tie directly to identifiable compliance, credit, or operational risk factors, not vague reputational discomfort. Many institutions are actively revisiting their enterprise risk management frameworks and removing reputational risk as a standalone category as a result.
What it doesn’t change: All existing safety and soundness, BSA/AML, OFAC, and consumer protection obligations remain fully in force. A bank can still decline or terminate a betting operator relationship based on genuine AML risk, unclear beneficial ownership, elevated chargeback exposure, or correspondent banking concerns, the rule specifically doesn’t prohibit de-risking itself, it addresses the use of reputational risk as a pretext when the real underlying justification doesn’t hold up to documentation requirements.
The Practical Implication for Betting Operators
This regulatory shift removes one specific justification banks previously leaned on, but it doesn’t eliminate the structural AML, compliance-cost, and correspondent-banking pressures that drive the majority of betting-business rejections. An operator with genuinely strong AML documentation, clear beneficial ownership disclosure, and a well-managed chargeback profile is now in a somewhat stronger position to challenge an account closure that isn’t grounded in a documented risk factor, but an operator with real underlying compliance gaps won’t find this rule protective, since those gaps remain entirely legitimate grounds for rejection.
Historical Context: Operation Choke Point and Its Legacy
Part of why this 2026 rule change matters comes from historical precedent. In 2013, US bank regulators were accused of informally targeting certain “high-risk” industries for reduced banking access as part of a Department of Justice initiative known as Operation Choke Point, a period that shaped how betting and other high-risk sectors have understood banking access ever since, and fueled ongoing debate about whether de-risking reflects genuine risk management or, at times, effective discrimination against lawful businesses in disfavored categories.
Whether regulators were incentivizing de-risking on ideological grounds, or banks were simply managing genuinely elevated compliance risk in these sectors, remains a debated question, but the practical effect on betting operators seeking banking relationships has been consistent regardless of the underlying motivation: reduced access, more scrutiny, and less appetite from mainstream banks to take on the category at all.
What This Means for Payment Infrastructure Strategy
Why This Pushes Operators Toward Specialized Providers
This entire dynamic is exactly why the specialized high-risk payment gateway providers covered in our guide on payment gateways for sports betting exist as a distinct category, mainstream banks’ structural aversion to the category, driven by the factors above, has created a genuine market need for providers who’ve built underwriting frameworks specifically for betting, rather than treating it as generically high-risk.
Documentation as the Actual Lever Operators Control
Given that de-risking is driven substantially by AML compliance cost and beneficial ownership clarity, an operator’s best lever for improving banking access isn’t disputing the classification, it’s proactively building and presenting the documentation that directly addresses the specific risk factors banks weigh:
- Clear, complete beneficial ownership disclosure, not just minimum-required documentation
- Documented AML and KYC program maturity (covered in depth in our AML/KYC guide, in a forex context, though the underlying principle applies broadly across high-risk verticals)
- Chargeback and dispute management infrastructure that demonstrates active risk control, not just reactive handling
- Clean, verifiable licensing status in a jurisdiction banks recognize and can independently confirm, a genuine reason Tier-1 licensing (Malta, UKGC) tends to unlock meaningfully better banking access than lower-tier jurisdictions, a theme covered in depth in our jurisdiction comparison guide
Correspondent Banking Considerations for International Operators
Betting operators processing across multiple jurisdictions should factor correspondent banking exposure into payment infrastructure planning explicitly, not just direct banking relationships, but the broader chain of institutions a cross-border payments flow actually passes through, since de-risking pressure at any point in that chain can disrupt payment flows even when the operator’s own direct banking relationship is stable.
Decision Framework: Building a Banking Strategy Around This Reality
If you’re a newly licensed operator building banking relationships for the first time:
- Prepare comprehensive AML, beneficial ownership, and compliance documentation before approaching any bank, rather than treating it as a follow-up request
- Go directly to specialized high-risk payment providers with documented betting-industry experience rather than expecting mainstream banks to extend an exception
If you’ve experienced a bank account closure or rejection:
- Request the specific, documented reason for the closure, particularly in US jurisdictions where the 2026 rule now requires closures to tie to identifiable risk factors rather than vague reputational concern
- Address whatever specific gap the documented reason reveals before reapplying elsewhere, rather than assuming the rejection reflects unfair treatment of the category broadly
If you’re processing internationally across multiple jurisdictions:
- Map your correspondent banking exposure explicitly, understanding that de-risking pressure anywhere in that chain can disrupt payment flows independent of your direct banking relationship’s stability
- Prioritize Tier-1 or Tier-1-adjacent licensing jurisdictions specifically for the banking access advantage they unlock, not just the market access they provide
If you’re evaluating whether the 2026 US reputational risk rule meaningfully improves your position:
- It’s a genuine, positive shift, but not a solution to underlying AML or compliance-documentation gaps, treat it as removing one specific bad-faith justification, not as reducing the actual underwriting bar a bank applies
Conclusion
Banks reject betting businesses primarily through structural de-risking, not individual judgment about any specific operator, driven by AML compliance cost, correspondent banking exposure, and historically, reputational concern layered on top of genuine regulatory risk factors. The 2026 US rule eliminating reputational risk as a standalone justification addresses part of this picture meaningfully, but the underlying compliance-cost and correspondent-banking pressures that drive most rejections remain fully in place.
For operators, the practical response isn’t waiting for banking access to improve on its own, it’s building the documentation (beneficial ownership clarity, AML program maturity, chargeback management) that directly addresses the specific risk factors banks weigh, while working with specialized high-risk payment providers who’ve built underwriting frameworks for this category specifically, rather than treating every rejection as evidence the category itself is unbankable.
Frequently Asked Questions
Q: Is “de-risking” the same thing as a bank rejecting an individual betting business for poor compliance?
A: No. De-risking specifically refers to banks restricting or exiting an entire category of business, like betting broadly, rather than evaluating individual merchants case-by-case, based on the compliance cost of managing that category’s risk profile outweighing the relationship’s value.
Q: Did the 2026 US regulatory rule make it illegal for banks to reject betting businesses?
A: No. The rule eliminated reputational risk as a standalone, sufficient justification for account closure, but all existing AML, BSA, OFAC, and safety-and-soundness obligations remain fully in force — banks can still decline betting operators based on genuine compliance, credit, or operational risk factors.
Q: Why does beneficial ownership matter so much to banks evaluating betting operators? A: If a bank can’t clearly identify the ultimate beneficial owners behind a business, that’s treated as an automatic red flag during underwriting, regardless of whether the underlying ownership structure is entirely legitimate, complex or offshore ownership structures, common among betting operators, face particular scrutiny here.
Q: Does licensing jurisdiction actually affect banking access for betting operators?
A: Yes, significantly. Tier-1 jurisdictions like Malta and the UKGC tend to unlock meaningfully better banking relationships than lower-tier or offshore jurisdictions, since verified, recognized licensing status functions as a credibility signal banks weigh directly during underwriting.
Q: What’s the single most effective thing a betting operator can do to improve banking access?
A: Proactively building and presenting comprehensive documentation, clear beneficial ownership disclosure, mature AML/KYC program evidence, and active chargeback management infrastructure, rather than waiting for a rejection to reveal what’s missing, since these are the specific risk factors banks weigh most heavily.
Q: Why do specialized high-risk payment providers exist specifically for betting operators? A: Because mainstream banks’ structural aversion to the category, driven by AML compliance cost, correspondent banking exposure, and historically reputational concern, has created genuine demand for providers who’ve built underwriting frameworks specifically for betting, rather than applying generic high-risk criteria that don’t account for the category’s specific risk profile.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment