
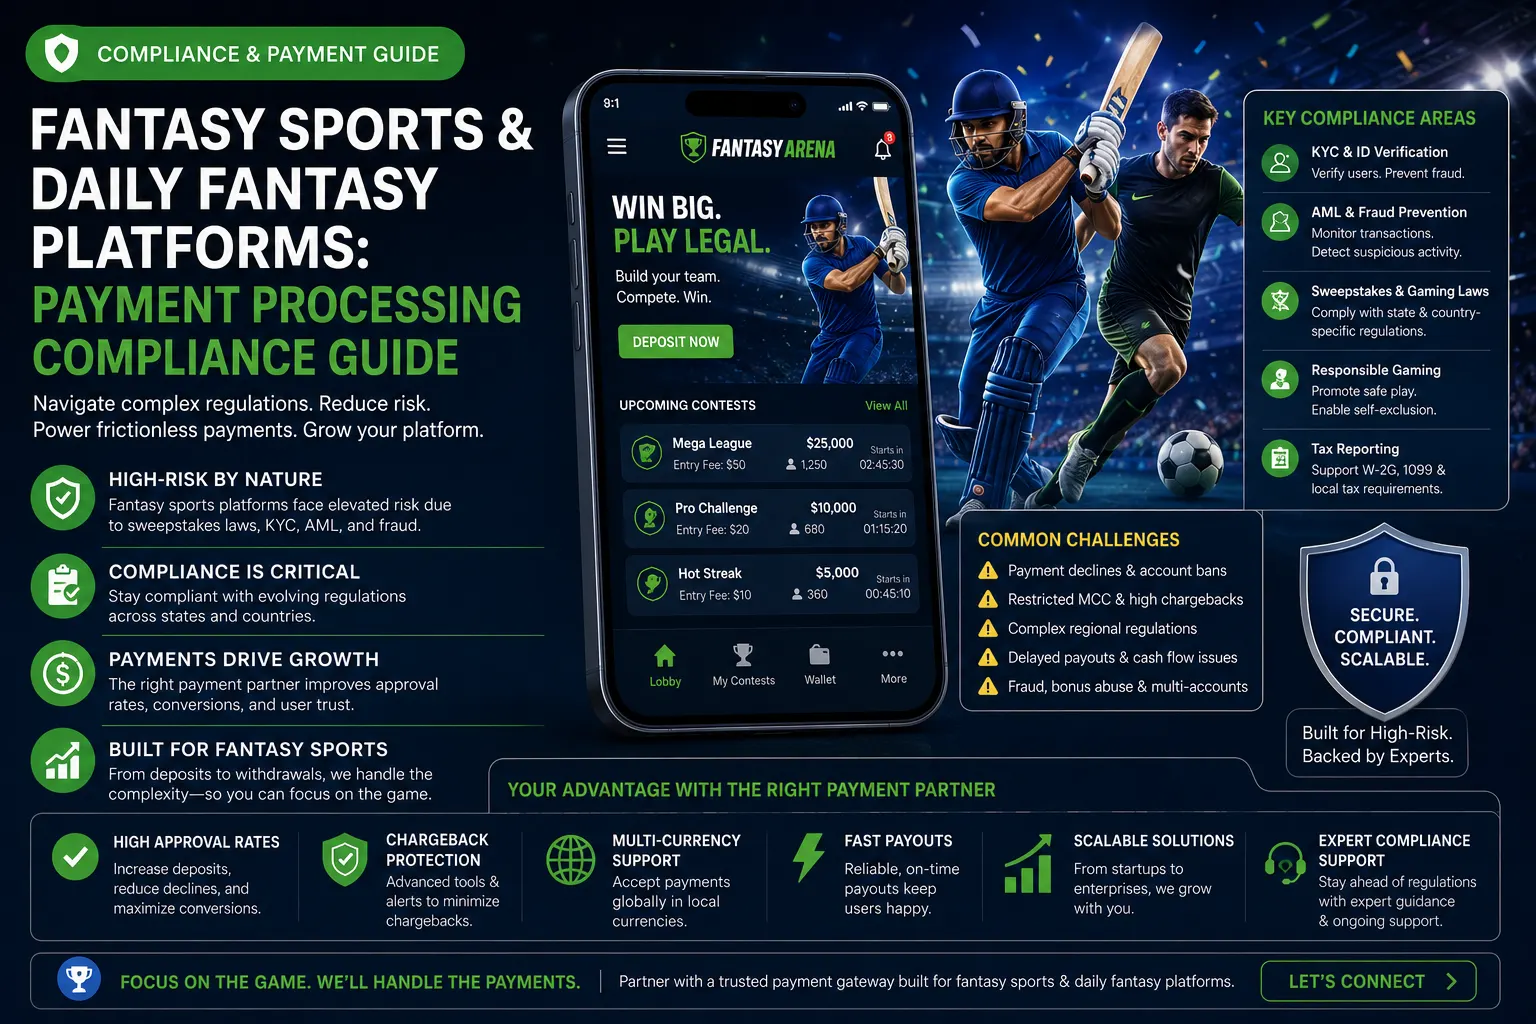
Daily fantasy sports occupies one of the murkiest classification zones in payment processing, legally defined as a game of skill in most US states, yet treated as gambling-adjacent by card networks, banks, and an increasing number of state attorneys general. For DFS operators, this ambiguity is not academic. It directly determines which payment providers will accept your account, what fees you pay, and how exposed your business is to sudden processing disruption. This guide breaks down the real compliance landscape for fantasy sports payment processing in 2026.
TL;DR
- DFS is exempted from federal gambling law under the 2006 UIGEA, but state-level classification varies significantly and is actively shifting in 2026
- California’s Attorney General issued an advisory opinion in July 2025 suggesting DFS contests may violate state gambling law, a non-binding but legally consequential signal that has already affected payment provider risk appetite
- Hawaii, Idaho, Montana, Nevada, and Washington prohibit DFS operation entirely; several additional states have active 2026 legislation tightening DFS regulation
- Mastercard’s revised merchant monitoring program now applies website scanning before a DFS merchant’s first transaction, a direct response to skill-vs-chance classification risk
- Processing fees for DFS platforms range from 3.5-6.0%, with rolling reserves of 8-15% depending on state mix and payment provider risk assessment
- EU operators face a different compliance picture entirely, most EU jurisdictions classify fantasy sports contests with cash prizes under gambling licensing regimes, requiring a fundamentally different payment compliance approach than the US
Why DFS Sits in Payment Processing Limbo
The core problem for DFS payment processing is that the “skill vs. chance” legal framework that protects fantasy sports from federal gambling classification in the US does not automatically extend to how card networks and payment providers assess risk. Visa and Mastercard apply merchant category codes based on actual business activity and risk profile, not on the legal nuance of how a state legislature has classified the contest format.
The Unlawful Internet Gambling Enforcement Act (UIGEA) of 2006 created a federal carve-out for fantasy sports, explicitly defining it as a game of skill rather than gambling, provided contests meet specific criteria: outcomes reflect the relative knowledge and skill of participants, prizes are established in advance, and winning is not based on the score of any single real-world team or game. This federal exemption is the foundation DFS operators have built on for nearly two decades.
State law is where the picture fractures. Most states permit DFS operation without specific licensing, treating it as exempted under the same skill-based logic as UIGEA. But a meaningful minority of states classify DFS as a form of gambling subject to licensing, taxation, or outright prohibition, and that minority is shifting in both directions as state legislatures and attorneys general revisit the question in 2026.
State-by-State Classification: Where DFS Stands in 2026
Understanding the current state classification landscape is essential context for any payment provider risk assessment, and it directly explains why payment processors treat DFS as a structurally elevated risk category regardless of an individual operator’s compliance posture.
States Where DFS Is Prohibited or Under Active Challenge
Hawaii, Idaho, Montana, Nevada, and Washington do not permit DFS operation, based on state attorney general opinions or existing gambling statutes that have not carved out a fantasy sports exemption. Texas has seen ongoing legal challenges to DFS operator activity, with the state’s classification remaining contested rather than settled.
California presents the most consequential 2026 development. The California Attorney General issued an advisory opinion in July 2025 indicating that DFS contests may violate the state’s gambling laws, a non-binding opinion, but one that gives local district attorneys a legal basis to pursue enforcement action against operators. California is one of the largest DFS markets in the country by population and engagement, and this advisory opinion has materially increased the perceived risk that payment providers attach to DFS merchant accounts with significant California user bases.
States With Active 2026 Legislative Movement
Illinois currently operates under the precedent of Dew-Becker v. Wu (2020), where the Illinois Supreme Court determined that head-to-head fantasy sports is predominantly skill-based and therefore not gambling, but the state does not formally license or regulate DFS operations, leaving a regulatory gap that several pending bills aim to close. New York is considering legislation (A6022/S2617) that would expand the statutory definition of interactive fantasy sports contests to explicitly include newer peer-to-peer formats, while clarifying these formats do not constitute sports wagering. Several states are advancing bills that would impose a 10% tax on adjusted gross fantasy contest receipts, signalling a broader trend toward formal regulation and revenue capture rather than prohibition.
The Sweepstakes and Prediction Market Adjacency Problem
A growing complication for DFS payment processing in 2026 is the regulatory crackdown on adjacent product categories, sweepstakes-style casino platforms and prediction markets, that has created a more cautious enforcement and payment risk environment across the entire fantasy and skill-gaming sector. States including Mississippi, Iowa, and Oklahoma have introduced legislation specifically targeting sweepstakes casino models, and payment providers underwriting DFS accounts increasingly scrutinise whether a platform’s contest mechanics resemble these more aggressively regulated formats.
Why Payment Providers Apply Enhanced Scrutiny to DFS Merchants
Card network monitoring frameworks have evolved specifically in response to the skill-vs-chance classification ambiguity that DFS occupies. Mastercard’s revised merchant monitoring programme, effective in 2026, now requires an initial website scan before any merchant is onboarded to accept Mastercard payments, a significant departure from the historical practice of monitoring only after a merchant began processing. This scan extends to restricted, members-only, and password-protected areas of a merchant’s platform, meaning the actual contest mechanics and prize structure are subject to review before the first transaction clears.
This shift directly affects DFS operators because the line between a compliant skill-based contest structure and a structure that resembles wagering is precisely what card network monitoring teams are now equipped to assess at onboarding rather than retroactively. Operators whose contest formats incorporate parlay-style or sportsbook-adjacent mechanics, increasingly common in newer DFS product categories, face the highest scrutiny.
Mastercard’s Excessive Chargeback Program threshold was also lowered in 2026, dropping from 220 basis points to 150 basis points (1.5%) across the US, EU, Canada, and Asia-Pacific. DFS platforms with elevated dispute rates from contest outcome disagreements or account funding disputes now breach this threshold at a meaningfully lower volume than under the prior framework.
Payment Provider Landscape for DFS in 2026
DFS Payment Provider Comparison
| Provider | DFS Acceptance | Avg Fee | Reserve Rate | State-Risk Underwriting | Notes |
|---|---|---|---|---|---|
| Nuvei | ✓ Strong | 3.5-5.0% | 6-10% | ✓ Detailed state mix review | Deep iGaming/DFS specialisation |
| PaymentCloud | ✓ | 3.9-5.5% | 8-12% | ✓ | Mid-size DFS operators |
| Durango Merchant Services | ✓ | 4.0-5.5% | 8-12% | ✓ | Start-up to mid DFS |
| eMerchantBroker (EMB) | ✓ | 4.0-6.0% | 10-15% | ✓ | Higher-risk state mix accepted |
| Stripe | Conditional | 2.9%+ | None | ✗ Limited transparency | Restricts after California opinion |
| Worldpay | ✓ Enterprise | Custom | Varies | ✓ | Large-scale, licensed operators |
Nuvei’s depth of experience in regulated iGaming makes it a natural fit for DFS operators, particularly those with state mix exposure that requires sophisticated, jurisdiction-aware underwriting. Stripe’s published policies have become more conservative toward DFS following the California Attorney General’s 2025 opinion, and operators relying on Stripe as a primary processor should maintain a dedicated high-risk backup relationship given the platform’s pattern of risk-based account actions with limited advance notice.
For DFS operators with EU user bases, the compliance picture changes substantially. Most EU jurisdictions classify fantasy sports contests involving cash prizes under national gambling licensing frameworks rather than exempting them as a skill-based activity. Operating in the UK, Malta, or other EU gambling-regulated markets requires the same licensing infrastructure, and the same specialist iGaming payment providers, as traditional sports betting, rather than the lighter-touch compliance environment that applies in most US states.
Building a Compliant DFS Payment Stack
Geofencing and state-level access control: is the foundational compliance requirement. DFS platforms must reliably restrict access to users in prohibited or unregulated states based on verified location data, not simply self-reported address information. Payment providers underwriting DFS accounts increasingly request documentation of the geofencing technology in place.
Contest structure documentation: that clearly demonstrates skill-based mechanics, entry criteria, scoring methodology, and prize structure determined independent of any single real-world game outcome, should be maintained and readily available for both card network compliance review and payment provider underwriting.
Age and identity verification: at account funding is required across virtually all US states with DFS activity, typically set at 18 or 21 depending on jurisdiction. This verification should occur before the first deposit, not retroactively.
Dispute and chargeback evidence packages: specific to contest outcome disagreements, entry confirmation, scoring rules acceptance, and payout calculation methodology, should be pre-built into the platform’s customer service and payment dispute workflow given the lowered Mastercard chargeback threshold.
Pros and Cons of DFS Payment Processing in 2026
Pros
- Specialist iGaming payment providers (Nuvei, EMB, Durango) have genuine DFS underwriting experience and actively accept this vertical
- The federal UIGEA exemption provides a stable compliance foundation that most US states continue to respect
- Geofencing and identity verification technology has matured significantly, making state-level compliance more operationally manageable than in earlier years
- New state legislation (NY, others) trends toward formal regulation and taxation rather than prohibition, a path to regulatory clarity rather than restriction
- EU iGaming payment infrastructure, while requiring full gambling licensing, is mature and well-supported for operators willing to pursue it
Cons
- California’s 2025 AG advisory opinion has already shifted payment provider risk appetite even though it carries no binding legal force
- Mastercard’s lowered Excessive Chargeback threshold (150bps) creates a materially tighter compliance margin for DFS platforms with contest-dispute-driven chargebacks
- Mainstream processors (Stripe, PayPal) apply increasingly conservative and sometimes opaque risk decisions to DFS accounts
- State-by-state classification fragmentation requires geofencing infrastructure investment that smaller DFS operators may find burdensome
- EU market entry requires full gambling licensing, a materially higher compliance bar than most US states currently impose
FAQ: Fantasy Sports Payment Processing Compliance
Does the California AG opinion mean DFS is now illegal in California?
No – the opinion is advisory and non-binding, meaning it does not change California law directly. However, it gives local district attorneys a legal basis to pursue enforcement action, and payment providers have responded by treating California DFS exposure as a meaningfully elevated risk factor in underwriting decisions.
Can a DFS platform use the same payment provider across all US states?
Yes, provided the provider conducts proper state-mix risk assessment and the platform maintains effective geofencing for prohibited states (Hawaii, Idaho, Montana, Nevada, Washington) and any states where local enforcement risk has increased. Several specialist iGaming processors offer unified payment infrastructure across the full range of US state classifications.
Do EU fantasy sports platforms need a gambling licence?
In most EU jurisdictions, yes – fantasy sports contests involving cash prizes are generally classified under national gambling regulation rather than exempted as skill-based activity, unlike the US federal approach under UIGEA. Operators expanding into EU markets should plan for gambling licensing requirements from the outset rather than assuming a skill-based exemption will apply.
How does Mastercard’s website scanning requirement affect existing DFS merchants?
The initial scan requirement applies to new merchant onboarding, but Mastercard’s enhanced monitoring also extends to ongoing review of restricted and password-protected platform areas for existing merchants. DFS operators should review their contest structure and platform documentation against current BRAM (Brand Reputation and Misuse) standards regardless of when they were originally onboarded.
What happens if a state where a DFS platform operates changes its classification mid-year?
Payment providers will reassess merchant risk and may adjust reserve requirements, fees, or in some cases restrict processing for users in the newly reclassified state. Operators should maintain active monitoring of state legislative activity and have a geofencing update process that can be deployed quickly in response to classification changes.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment