
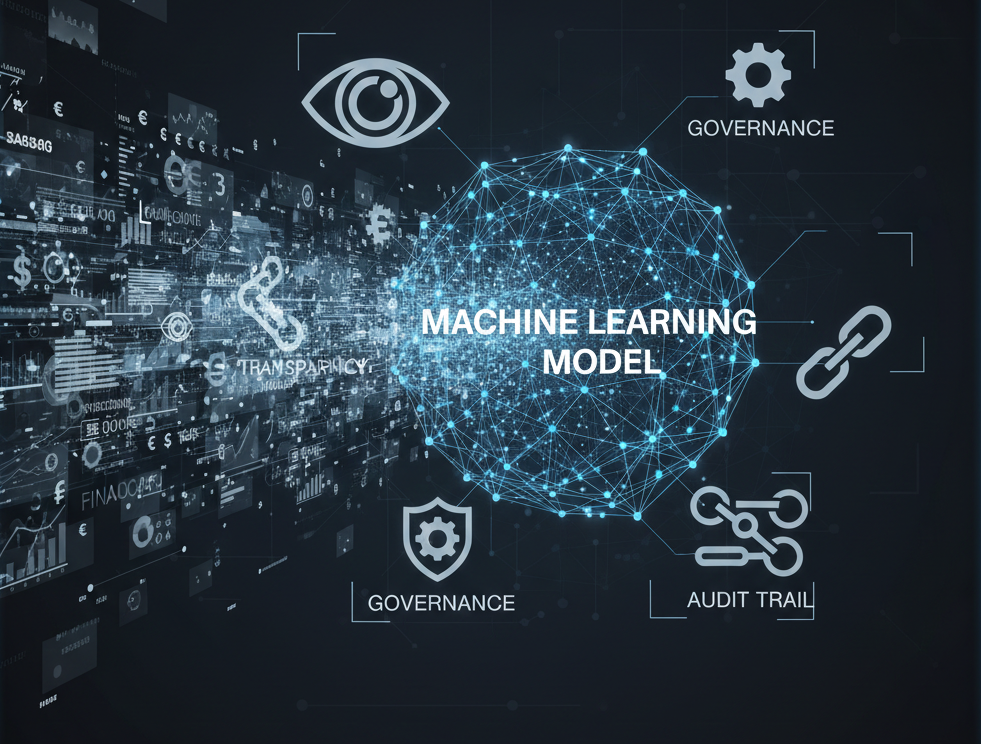
Algorithms increasingly decide who gets a loan, how much interest they pay, which transactions are flagged as suspicious, and how investments are allocated. As financial institutions rely more heavily on artificial intelligence and machine learning, decision-making in finance is becoming faster, more scalable—and more opaque.
While algorithmic finance promises efficiency and objectivity, it introduces a critical challenge: bias.
Contrary to popular belief, algorithms are not inherently neutral. They reflect the data they are trained on, the assumptions built into their design, and the objectives they are optimized to achieve. When these systems operate at scale, even small biases can translate into systemic financial inequality.
This article explores the nature of bias in algorithmic finance, why it matters, where it emerges, and how financial institutions can address it responsibly.
What Is Algorithmic Bias in Finance?
Algorithmic bias occurs when automated systems produce outcomes that unfairly disadvantage certain individuals or groups. In financial services, this bias can affect:
- Credit approvals
- Interest rates
- Insurance pricing
- Fraud detection
- Investment recommendations
Bias is not always intentional. Often, it emerges from:
- Historical data reflecting past discrimination
- Proxy variables that indirectly encode sensitive attributes
- Feedback loops that reinforce existing patterns
When algorithms make decisions faster and at greater scale than humans, bias becomes harder to detect—and far more damaging.
Where Bias Appears in Financial Systems 
Credit Scoring and Lending
Machine-learning models often rely on non-traditional data such as transaction history, employment patterns, or online behavior. These variables can act as proxies for protected characteristics, leading to unequal access to credit.
Fraud Detection Systems
Fraud models may disproportionately flag certain geographies, transaction types, or demographic patterns, resulting in higher false positives and customer friction for specific groups.
Algorithmic Trading
Trading algorithms trained on historical market behavior may reinforce volatility or exploit inefficiencies that disadvantage retail investors.
Insurance Underwriting
AI-driven pricing models can unintentionally penalize individuals based on correlations rather than actual risk.
In each case, the issue is not automation itself—but unchecked automation.
Why Bias Is More Dangerous in Algorithms Than Humans
Human decision-making is imperfect, but algorithmic bias poses unique risks.
Scale and Speed
Algorithms operate continuously and at scale. A biased decision is not isolated—it is repeated thousands or millions of times.
Opacity
Many advanced models lack explainability. When outcomes cannot be easily interpreted, identifying bias becomes difficult.
Perceived Objectivity
Algorithmic decisions are often trusted more than human judgment, even when flawed. This false sense of neutrality delays scrutiny.
Feedback Loops
Biased outcomes influence future data, reinforcing the same patterns and amplifying inequality over time.
Regulatory Attention Is Intensifying
Global regulators are increasingly focused on algorithmic bias in finance.
Key concerns include:
- Fair lending compliance
- Discriminatory outcomes
- Transparency and explainability
- Accountability for automated decisions
Emerging regulatory frameworks emphasize:
- Model governance
- Bias testing and monitoring
- Human oversight
- Clear documentation
Financial institutions can no longer treat bias as a technical issue—it is a governance and compliance priority.
Implications for Financial Institutions
Financial services play a foundational role in economic participation. When algorithms deny access to credit, insurance, or investment opportunities, the consequences extend beyond individual transactions.
Ethical risks include:
- Reinforcing socioeconomic inequality
- Excluding vulnerable populations
- Damaging institutional trust
- Creating reputational and legal exposure
Responsible algorithmic finance requires aligning technological innovation with ethical responsibility.
Can Bias Be Eliminated?
Bias cannot be fully eliminated—but it can be managed, mitigated, and monitored.
Effective strategies include:
- Diverse and representative training data
- Regular bias audits and stress testing
- Explainable AI models for high-impact decisions
- Human-in-the-loop oversight
- Clear accountability frameworks
Institutions that proactively address bias position themselves ahead of regulatory pressure and public scrutiny.
Bias as a Strategic Risk
Ignoring algorithmic bias is not just unethical—it is strategically risky.
Unchecked bias can lead to:
- Regulatory penalties
- Customer attrition
- Brand damage
- Legal challenges
- Loss of market trust
Conversely, organizations that embed fairness into AI design gain:
- Stronger customer confidence
- Better regulatory alignment
- More resilient decision systems
Fairness is becoming a competitive differentiator in financial services.
The Future of Algorithmic Finance
As AI adoption deepens, the financial sector must evolve from automation-first thinking to responsibility-first design.
The future will favor institutions that:
- Treat algorithms as accountable actors
- Combine innovation with transparency
- Balance efficiency with fairness
- Invest in governance as much as technology
Bias is not a side effect—it is a core design challenge.
Conclusion
Algorithmic finance is reshaping how money moves, risks are assessed, and opportunities are allocated. While automation offers powerful advantages, it also introduces the risk of systemic bias at unprecedented scale.
The challenge for financial institutions is not whether to use algorithms—but how to govern them responsibly.
Addressing bias requires transparency, oversight, ethical intent, and continuous vigilance. In a world where machines increasingly shape financial outcomes, fairness is no longer optional—it is fundamental to the future of finance.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment