
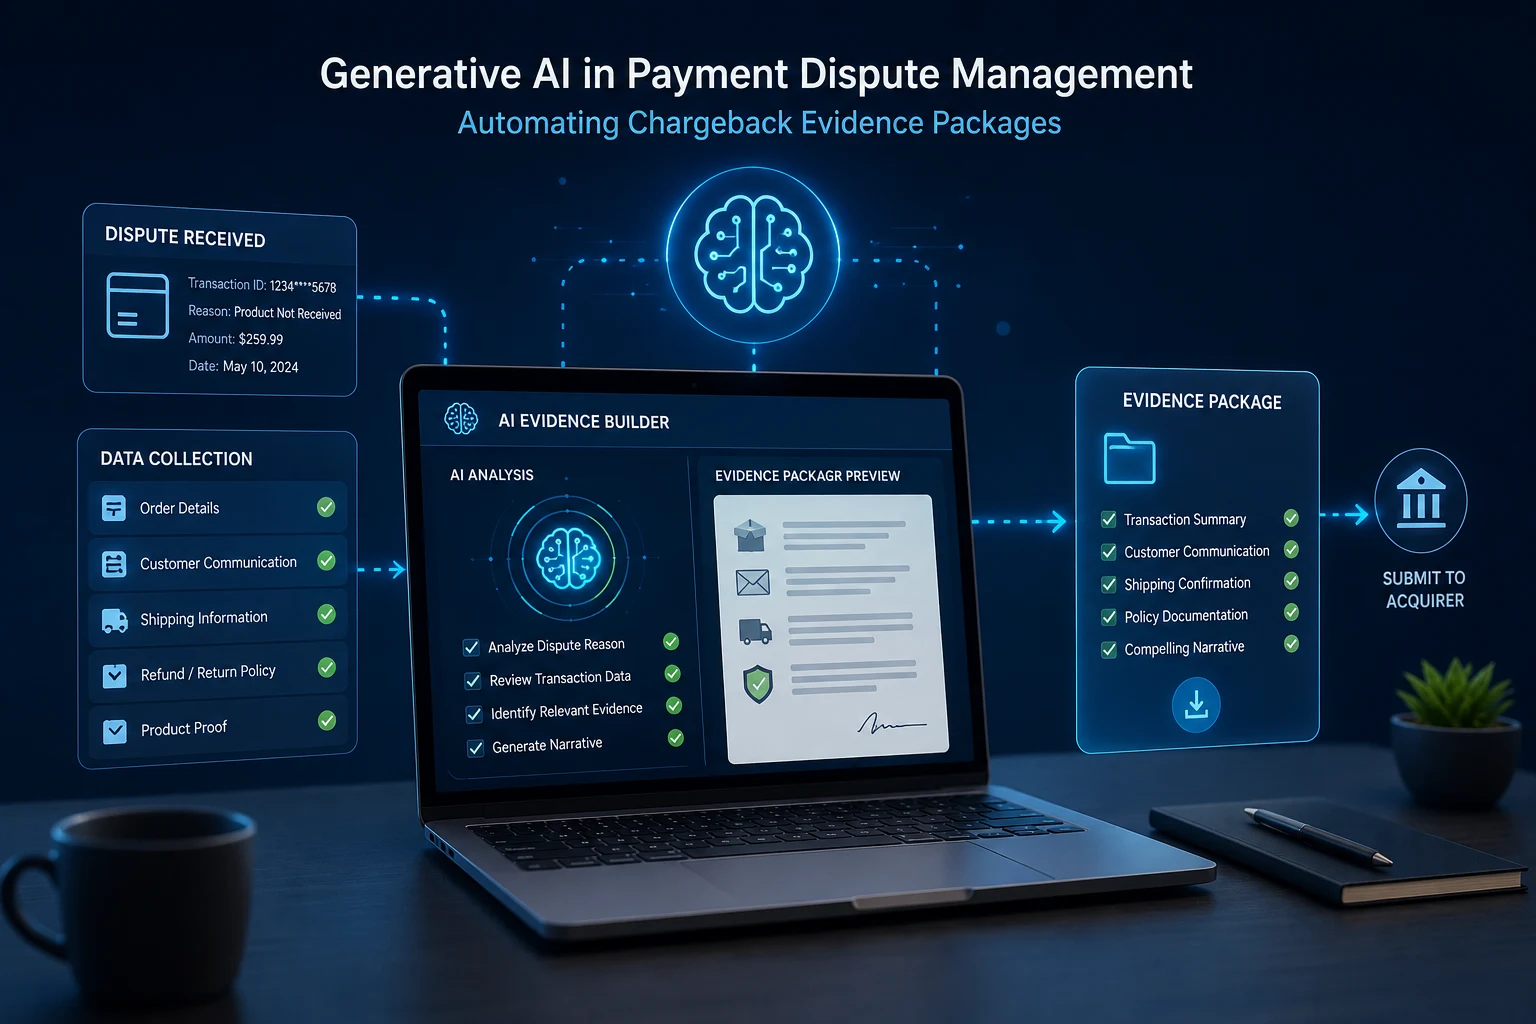
Chargeback disputes are one of the most resource-intensive processes a high-risk merchant faces, and most of that resource is spent manually assembling evidence packages under card network deadlines that leave little room for error. Generative AI is changing that, turning a process that once took hours of analyst time into one that takes minutes. This guide explains exactly how GenAI automates chargeback evidence packages, which platforms are doing it well in 2026, and what payment operators need in place before deploying.
TL;DR
- Merchants win only 32% of chargeback disputes on average, poor evidence structure, not absent evidence, is the leading cause of avoidable losses
- Global chargeback dispute volume is projected to reach 337 million annually by 2026, making manual representment workflows unsustainable at scale
- Generative AI automates evidence aggregation, reason-code-specific narrative construction, and response letter drafting, cutting build time from hours to minutes
- GenAI dispute platforms report 20-40% win rate improvements over manual representment on disputes where evidence exists but is poorly organised
- Visa’s Compelling Evidence 3.0 (CE3.0) framework rewards data-rich, structured submissions, precisely what GenAI is built to produce
- Clean data infrastructure and payment gateway integration are the prerequisite; GenAI organises evidence, it does not create it
Why Manual Dispute Management Breaks Down at Scale
For most high-risk merchants, a single chargeback dispute means pulling evidence from multiple disconnected systems, the payment gateway, CRM, shipping provider, customer communications platform, and order management system, assembling it into a coherent package, and submitting it within card network deadlines that typically run 20-45 days from the dispute date.
At low volumes this is manageable. At the transaction volumes typical of high-risk merchant accounts in gaming, forex, or subscription billing, it becomes an operational bottleneck that drives errors, missed deadlines, and avoidable losses. The average cost to manually process a single chargeback dispute runs between $25 and $50 in direct staff time, according to Chargebacks911. Across hundreds or thousands of monthly disputes, that overhead compounds into a significant cost centre with no strategic upside.
The outcome data makes the case more clearly. Merchants win only 32% of chargeback disputes on average. The most commonly cited reason for avoidable losses is not an absence of evidence, it is evidence that is incomplete, unstructured, or misaligned to the specific evidentiary requirements of the reason code the dispute was filed under. The data to win is there; it is just not being assembled in the format that gets results.
Global chargeback dispute volume is also growing. Projected to reach 337 million annual disputes by 2026, the volume trajectory makes any purely manual response strategy structurally unsustainable for high-risk payment operators managing more than a few hundred disputes per month.
What Generative AI Actually Does in Dispute Management
Generative AI does not simply automate document retrieval or populate a template. It reads, interprets, and synthesises evidence from multiple data sources, then produces a structured, formatted dispute submission calibrated to the specific evidentiary requirements of each chargeback reason code.
This is a meaningful distinction from rule-based automation, which can route cases and fill known fields but cannot generate a factual narrative argument, adapt evidence presentation to the nuances of a specific reason code, or draft a response letter that addresses the cardholder’s stated claim directly. GenAI handles all three, consistently, at volume, and without the variability that comes with rotating analyst teams.
Evidence Aggregation
The first task is pulling all relevant evidence automatically. GenAI dispute platforms integrate with the merchant’s payment processing stack, gateway, CRM, order management, and fulfilment systems, and retrieve the full transaction record, customer account history, delivery confirmation, device and IP data, and any customer service interactions linked to the disputed order.
This aggregation step alone eliminates the manual data-gathering phase that accounts for 40–60% of total dispute preparation time, based on operator benchmarks reported by Midigator. For offshore merchants whose evidence sits across multiple payment providers and regional systems, the integration layer is particularly valuable.
Narrative Construction
GenAI then maps the aggregated evidence against the dispute’s reason code. A reason code 13.1 (Merchandise Not Received) requires different evidence emphasis than a 10.4 (Other Fraud, Card Absent Environment) or a Mastercard 4853 (Cardholder Dispute, Not as Described). The model builds a factual narrative that presents available evidence in the sequence and format most likely to satisfy the specific burden of proof required for that code.
This is precisely where most manual processes fail. Evidence is frequently submitted in chronological order rather than structured around what the card scheme’s rules actually require as proof for the dispute category in question.
Response Letter Drafting
The final output is a complete representment package: a formatted merchant response letter, ordered evidence attachments, and a cover summary. GenAI drafts the response letter in the language and structure required by the acquiring bank or card scheme, specific, factual, and tied to the dispute timeline. Leading platforms generate multiple versions calibrated to different issuer adjudicator preferences, using historical outcome data to select the approach most likely to succeed with that issuing bank.
How a GenAI Evidence Package Gets Built: Step by Step
Step 1 – Dispute intake: The chargeback notification arrives via the payment gateway or acquirer portal. The GenAI platform logs the dispute, extracts the reason code, ARN, and dispute amount, and starts the response deadline countdown automatically.
Step 2 – Automated evidence pull: The platform queries all connected data sources simultaneously: the payment gateway for the transaction record, CRM for customer account history and communication logs, order management for fulfilment and delivery data, and device intelligence for IP address, geolocation, and fingerprint captured at the time of purchase.
Step 3 – Reason code mapping: The model maps the dispute’s reason code to the evidentiary requirements defined under Visa’s CE3.0 framework or Mastercard’s equivalent dispute resolution rules. It identifies which evidence documents are present, which are missing, and assigns a representment confidence score. Low-confidence cases are flagged for human review before any submission decision.
Step 4 – Package generation: The model generates the evidence narrative and response letter, structures the attachment sequence in the required format, and produces a submission-ready package. For high-risk merchant accounts with high transaction volumes, this step runs in parallel across hundreds of open disputes simultaneously.
Step 5 – Review and submission: Depending on platform configuration and dispute value, the package is either auto-submitted or routed to a human reviewer. Most platforms support threshold-based auto-submission, lower-value, high-confidence disputes go automatically; high-value or ambiguous cases get a review queue.
What Goes Into a GenAI-Built Evidence Package
A complete GenAI-generated evidence package for a high-risk merchant dispute typically includes:
- Transaction record: gateway confirmation, authorisation code, amount, timestamp, and settlement currency
- Customer account history: account creation date, prior transactions, login activity, and any prior disputes or refund requests
- Delivery or service confirmation: tracking number and proof of delivery for physical goods; IP-confirmed access logs for digital goods or subscription services
- Customer communication log: all email, chat, or support ticket exchanges related to the disputed order, auto-extracted and timestamped
- Device and IP intelligence: geolocation match, device fingerprint, and session behavioural data at the point of transaction
- Policy acceptance record: refund, cancellation, and terms of service confirmation with the customer’s acceptance timestamp
- Merchant response narrative: the GenAI-drafted factual summary aligning evidence to the specific reason code requirements
Traditional vs GenAI Dispute Management: Head-to-Head
| Factor | Manual Representment | GenAI-Assisted |
|---|---|---|
| Evidence build time | 2-4 hours per dispute | 5-15 minutes per dispute |
| Data source coverage | Analyst-dependent; often incomplete | Automated across all integrated platforms |
| Reason code calibration | Variable – analyst-dependent | Consistent model-driven mapping per code |
| Response letter quality | Inconsistent | Structured, code-specific, formatted |
| Average win rate | ~32% | 40-55% on strong-evidence disputes |
| Deadline compliance | Manual tracking; missed deadlines common | Automated monitoring with alerts |
| Cost per dispute | $25-$50 in staff time | $3-$8 platform cost + minimal review |
| Volume scalability | Breaks down above ~200 disputes/month | Scales linearly with dispute volume |
GenAI Dispute Platforms Worth Knowing in 2026
Chargebacks911: is the most established platform in the high-risk dispute management space, combining GenAI-assisted package generation with managed services for complex cases. Its integration depth covers most major payment gateways used in high-risk merchant services, and it is one of the few platforms with documented performance benchmarks in gaming and adult content verticals.
Disputifier: is an AI-native tool built for direct payment gateway and Shopify integration. Its GenAI layer focuses on automated representment for digital goods and subscription merchants, with real-time representment confidence scoring to triage which disputes are worth submitting versus accepting.
Midigator: (now part of Equifax) combines GenAI-assisted document generation with detailed dispute analytics. It is particularly useful for high-risk payment operators who need both automated representment and root cause analysis to feed chargeback prevention upstream.
Verifi (Visa) and Ethoca (Mastercard) operate pre-dispute resolution networks that resolve disputes through transaction data sharing before they reach the formal chargeback stage. These are not GenAI representment builders, but they are complementary, reducing the dispute volume that reaches representment in the first place.
What High-Risk Merchants Need in Place Before Deploying
Data quality is the non-negotiable prerequisite: GenAI dispute tools produce complete packages only when the merchant’s connected systems are clean and comprehensive. Disorganised CRM records, missing delivery confirmations, or disconnected customer communication logs limit what the model can build. Audit data infrastructure before integration, incomplete data produces incomplete packages.
Reason code coverage matters: Not all platforms handle every Visa and Mastercard reason code with equal capability. Map your most frequent dispute reason codes against the platform’s documented coverage, particularly for the codes most common in your specific high-risk vertical.
Visa CE3.0 readiness requires gateway-level logging: Visa’s Compelling Evidence 3.0 framework rewards merchants who can demonstrate two prior undisputed transactions from the same cardholder on the same device. This requires payment gateway logs that capture device fingerprint and IP data at the transaction level. Confirm your payment providers log this data in a CE3.0-compatible format before deployment.
Set auto-submission thresholds carefully: Automatic submission without human review works well for low-value disputes with high representment confidence. For high-value disputes in high-risk payment environments, a human review step prevents flawed packages from damaging representment credibility with the acquirer over time.
Pros and Cons of GenAI in Chargeback Dispute Management
Pros
- Cuts evidence build time from 2-4 hours to under 15 minutes per dispute, essential for high-volume high-risk operators
- Consistent reason-code-specific structuring removes the analyst variability that drives avoidable representment losses
- Automated deadline monitoring eliminates missed response windows, which forfeit disputes regardless of evidence strength
- Win rate improvements of 20-40% on strong-evidence disputes versus manual representment reduce chargeback cost ratios materially
- Platform cost of $3-$8 per dispute versus $25-$50 in manual staff time delivers clear ROI from low volumes
Cons
- Output quality depends entirely on data completeness, missing CRM records or disconnected systems produce weak packages regardless of model sophistication
- Integration with payment gateway, order management, and CRM systems requires engineering investment before deployment
- Friendly fraud disputes with genuinely thin evidence remain difficult regardless of how well the package is assembled
- Auto-submission without review creates risk of submitting low-confidence packages on complex or high-value cases
- Platform pricing models vary; per-dispute costs at very high volumes can erode unit economics, validate at scale before full deployment
FAQ: Generative AI in Chargeback Dispute Management
Does GenAI actually improve chargeback win rates, or is this vendor marketing?
The documented improvements, 20–40% over manual baseline, apply specifically to disputes where the merchant had the evidence but was presenting it poorly. GenAI does not manufacture evidence. On disputes with genuinely thin or absent evidence, win rate improvements are marginal. The gains are real but bounded by what the underlying data actually supports.
How does Visa CE3.0 interact with GenAI dispute tools?
CE3.0 rewards merchants who can document two prior undisputed transactions from the same cardholder on the same device and IP address. GenAI platforms with CE3.0 awareness automatically retrieve and format this prior transaction data when it exists in the connected payment gateway logs. Merchants whose gateways do not capture device and IP data at the transaction level cannot satisfy CE3.0 requirements regardless of which platform they use.
Can GenAI handle the dispute profiles specific to high-risk verticals?
Capability varies significantly by platform. Platforms with dedicated high-risk merchant experience, Chargebacks911 in particular, have reason code models calibrated to the dispute patterns common in gaming, adult content, and subscription billing. Generic dispute platforms may lack coverage of the specific reason codes and evidence requirements that dominate in high-risk payment environments.
What happens to rejected representments – does the platform learn?
On well-built platforms, rejection outcomes feed back into the model’s performance data, improving future package generation for that reason code, evidence configuration, and issuer combination. Platforms that track win rates by reason code, merchant category, and acquirer provide the most useful feedback loop for continuous calibration.
Do offshore merchants face specific limitations with GenAI dispute platforms?
The main constraint is integration depth. Offshore merchants using regional payment providers or less common gateways may have limited API connectivity with mainstream GenAI dispute platforms. Evidence from non-integrated sources must be uploaded manually, which partially offsets the automation benefit and introduces the manual bottleneck the platform was deployed to eliminate.
Comments
No comments yet. Be the first to share your thoughts.
Leave a comment